Blogs

Regulation of Mining and Critical Minerals in East Africa: A comparative overview of Tanzania, Uganda, Kenya, Rwanda and Burundi

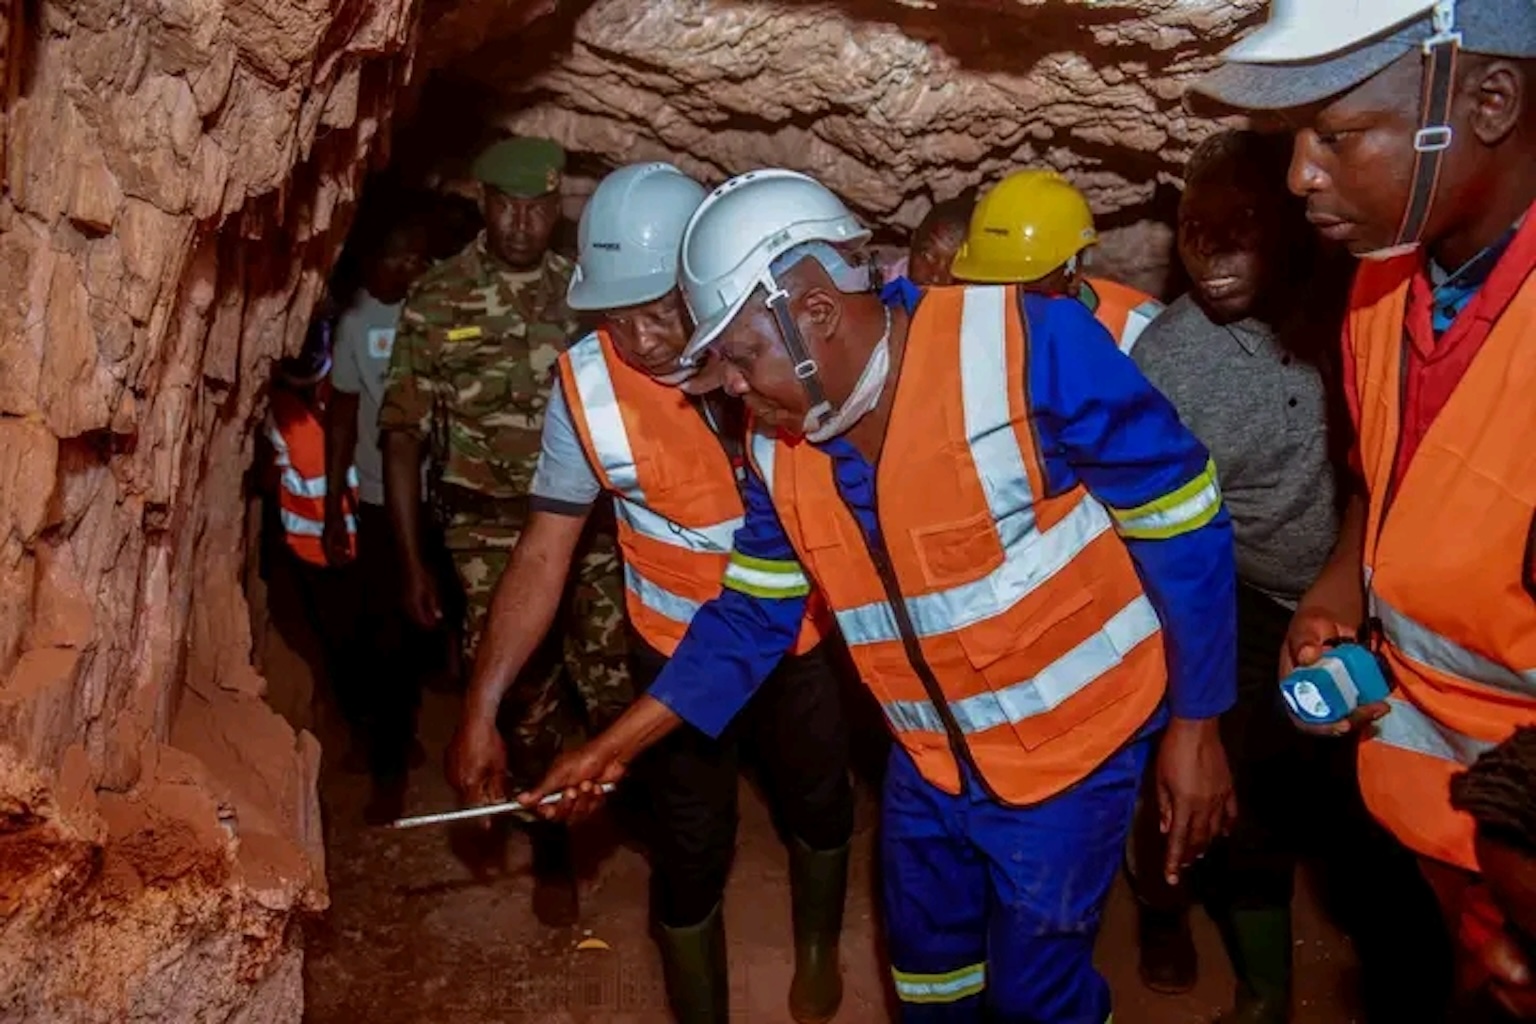
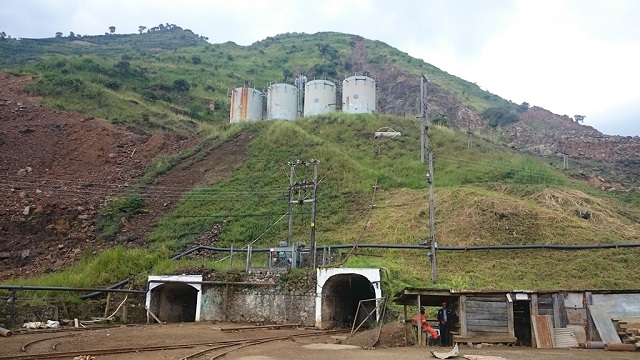
Photo Credit: President of Burundi, HE Évariste Ndayishimiye inspects a Mine in Burundi

Authors: Dr Ange-Dorine Irakoze, Moses Kulaba, & Eva Kihupi, Governance and Economic Policy Centre

Executive Summary

There is an increasing discussion as to whether Africa’s critical minerals potential can contribute to lasting economic benefits for mineral rich countries. This short study report provides an overview of the current legal regulatory terrain governing mining in selected East Africa Community (EAC) Countries with a particular focus on mining regulatory framework in Tanzania, Kenya, Uganda, Rwanda and Burundi.

It highlights the critical mineral potential, policy and legal framework governing the allocation of mining rights, taxation and fiscal regime, exemptions and incentives, local content provisions, land compensation and environmental regulations, Artisanal and Small Mining (ASM), Minerals Value Addition and Trading. The findings suggest that despite the developments in legal reforms over the last decade, progressive movement on critical minerals regulation and safeguards of environmental, community rights and responsible business conduct has remained varied across countries and stagnant

This report cannot be used as an exclusive source document on East Africa’s minerals and mining regulatory landscape. Interested stakeholders such as investors are encouraged to reach out to the respective EAC governments for detailed updated information. The findings, however, provide essential topline information for key stakeholders (government, mining companies, investors, researchers, members of legislative bodies and civil society) on the general regulatory landscape of mining in the EAC.

Background

Mining is a critical sector for East Africa’s development.  So far Mining contributes about 2.3% of GDP and a leading foreign exchange earner within the nontraditional exports of EAC member states[1]. The EAC region is endowed with a variety of minerals resources such as gold, diamonds, copper, coal, iron ore oil, gas, fluorspar, titanium and zirconium, cobalt and nickel.  These mineral resources present an opportunity for development of the mining industry, which is currently underdeveloped. Further, the sector has great potential for economic growth, employment opportunities and spearheading both the forward and backward linkage of the region’s economy.

Respective EAC member states aim to attract more investments and increase the contribution of the mining sector significantly with Tanzania aiming for 10% by 2026[2]. Over the last decade the EAC member states have recorded an increase or upsurge in exploration for critical energy transition minerals and it is projected that their mining activities will increase over the next decade.  However, realising full benefits from the mineral wealth is held back by weak or unpredictable regulatory regimes, economic injustice and environmental concerns.

The UN and IEA warns that increasing exploration and mining activities for critical minerals will potentially aggravate harm in mining communities. And there is an increasing discussion as to whether Africa’s infamous resource curse can be reversed and its critical minerals potential can contribute to lasting economic benefits for mineral rich countries.

Critical Minerals are loosely defined as raw minerals and materials required to support the clean industrial technology and energy transition to a more sustainable low carbon future (IGF:2022). These minerals include copper, lithium, nickel, cobalt, tantalum, manganese and graphite and other rare earth elements. Lithium, nickel and cobalt are core components of batteries, like those that power electric vehicles. Rare earth elements are part of the magnets that turn wind turbines and electric motors. Copper and aluminum are used in massive amounts in power transmission lines (UNEP).[3]   
There is a surge in demand for these minerals, with the IEA estimating that demand for graphite and copper will increase by folds by 2050 (IEA). At least 900,000 tons of graphite is required to manufacture 12 million EVs [4]. Their distinct characteristics, spatially restricted distribution and significant role they are playing in driving the technology to support a clean future makes them a special type of minerals warranting special governance emphasis. Because of their limited geographical occurrence, amidst surging demand, it is imperative that their extraction is just, fair and does not aggravate economic injustices, more harm and human rights abuses.

With out proper policy and legal regulatory governance frameworks and strategic re-positioning, EAC’s mining sector and its critical green transition minerals rich countries could again miss out from this 4th industrial mineral revolution boom.

 Rationale

The EAC hosts vast deposits of critical and strategic energy transition minerals such as coltan, nickel, tantalum, platinum, niobium, copper and other Rare Earth Elements vital in driving the green technological revolution to a cleaner energy future. Tanzania holds 3rd largest graphite reserves in Africa and accounting for about 5% globally, Rwanda is a leading producer of the 3Ts (Tantalum, Tungsten and Tin) , Uganda has vast deposits of Copper, Kenya leads in Platinum and Burundi has the second reserve of coltan in East Africa.

The admission of the Democratic Republic of Congo (DRC) to the EAC in 2022 increased the region’s position as a global player in the critical and strategic mineral’s space as the DRC holds and accounts for about 68% of the global cobalt production. Graphite, copper and Cobalt are key ingredients in the manufacture of Electric Vehicle components. The presence of abundant critical minerals is not enough. This abundance must be accompanied by concomitant conducive regulatory frameworks to attract investment while at the same time maximizing value and harnessed benefits for mineral rich countries.

The EAC treaty states that natural resources must be harnessed for the benefit of citizens and Article 114 of the treaty requires member states to cooperate in natural resource management but this commitment is fully to be achieved. There is no harmonized approach to mining governance and the EAC model mining law remains unpassed.  The transition to a clean future provides an opportunity for the EAC Green Transition Mineral rich countries to benefit from their mineral wealth.

Yet the history of governance and management of the mineral sector has so far yielded low dividends for mineral-rich countries in the region. There is an increase in exploration for critical green transition minerals but this is undermined by concerns for environment safety and economic justice for mining communities.  It is evident that without proper regulation environment and strategic positioning, critical green transition minerals rich countries could again miss out from this mineral boom.

Proper Governance of the mining sector can help the EAC address these challenges and thereby void the infamous resource curse that has bedeviled some of its member states for decades. Effective governance and regulatory framework for critical minerals can catapult the region into a major global player in the future green industrial and technological revolution, without aggravating human rights and more harm.

The Constitutions of all the EAC member states provide that natural resources and all minerals are public property vested in the President as Head of State or governments in trust on behalf of their citizens.  With proper governance and regulation, citizens can have a stronger say in the governance of their Natural Resource wealth. Adequate policy and legal frameworks facilitate a predictable investment regime and increased government and corporate accountability, ensuring ethical investment and that benefits from the available mineral wealth are shared equitably.

Overview of EAC’s Mineral Resources 


Country

Precious metal, Gemstones & Semi-Precious Metal

Metallic Minerals

Industrial minerals

Burundi

Gold

Tin, Nickel, copper, cobalt, niobium, coltan, vanadium, tungsten

Phosphate, Peat

Kenya

Gemstones, gold

Lead, zircon, iron, titanium

Soda ash, flourspar, salt, mica, chaum, oil, coal, diatomite, gypsum, meers, kaolin, rare earth

Rwanda

Gold, gemstones

Tin, tungsten, tantalum, niobium, columbium

pozzolana

Tanzania

Gold, diamond, gemstones, silver, PGMs

Nickel, bauxite, copper, cobalt, uranium

Coal, phosphate, gypsum, pozzolana, soda ash, gas

Uganda

Gold, diamond

Copper, tin, lead, nickel, cobalt, tungsten, uranium, niobium, tantalum, iron

Gypsum, kaolin, salt, vermiculite, pozzolana, marble, soapstone, rare earth, oil

South Sudan

Gold, silver

Iron, copper, tungsten, zinc, chromium

Oil, mica

Democratic Republic of Congo -DRC

Gold, diamond, silver, gemstones

Cobalt, Nickel, bauxite, copper, uranium, Coltan, Tantalum


 Objective

The overall objective of this study was to provide an overview of the mining regulatory frameworks of five selected East African Community (EAC) member states: Tanzania, Kenya, Uganda, Rwanda and Burundi, with a view of identifying potential gaps and making recommendations to strengthen overall governance of the sector and mining for critical minerals in identified member states and the EAC generally.

Methodology and Scope

The study compares the mining and critical-minerals regulatory frameworks of five East African Community partner states: Tanzania, Uganda, Kenya, Rwanda and Burundi. The five were selected on the basis of their critical-mineral endowment and the accessibility of their primary legal frameworks; the Democratic Republic of Congo and South Sudan are included in the regional resource table for context. The analysis is based on a desk review of national constitutions, mining and minerals laws and their subsidiary regulations, fiscal and investment legislation, Extractive Industries Transparency Initiative (EITI) reports, and official government and industry data available up to the second quarter of 2026. The depth of treatment varies between countries according to the availability of primary legal sources in each jurisdiction. All quantitative figures are reproduced as published by the cited sources and have not been independently audited. Before relying on the information contained in this report and subsequent briefs, readers are advised to check with the relevant national authorities to see if any legislative changes or revisions to the figures have occurred since its publication.

From this report, stakeholders can take notice of the gaps and determine whether the current mining regulatory regime in the EAC is suited for the evolving mining context driven by a surge in demand for critical minerals. And whether the EAC member states require a facelift of their minerals regulatory regimes to attract large new investments in the critical minerals sector while at the same time mitigating harm. At the same time, it provides some key takes as guard rails against exploitative mining practices for critical minerals and the mining sector generally, with recommendations as advocacy pointers for the necessary reforms required to maximize value and benefits from mining generally, mitigating harm from mining of critical minerals and advancing a just energy transition.

Key findings

  1. The study shows that a new wave of policy and regulatory regimes have been passed in the last 5-10 years replacing old regulatory regimes of the 1990s. However, it reveals disjointed and truncated approach to mineral regulation across countries, with significant gaps in regards to governance of critical transition minerals in particular.  While some countries such as Tanzania have developed draft strategic plans to guide the sector, which also proposes the country’s strategic and critical mineral lists, other countries have no distinct strategies and have an omnibus regulatory approach covering critical minerals within the ambits of existing mining laws, while others have not even started.

2. Moreover, there is no harmonized EAC regulatory framework on treatment of key, essential provisions for mineral governance. EAC member states have taken a lonesome and national centric approach to regulation with each country developing its own regulatory regime, competing to offer a raft of incentives and exemptions to attract investment, varying levels of state participation and free carried interests, fiscal terms and royalty treatment, value addition and mineral beneficiation, local content, community participation rights, land compensation and benefit sharing.  

3. There are also variations in treatment of environmental rights and responsible business conduct thresholds.  For instance, Uganda, Kenya and Rwanda’s regulatory frameworks provide for mandatory community consultation, participation and rights to negotiate Community Development Framework Agreements (CDAs) with mining companies.  The Community Development Framework must be prepared in both English and local languages. Meaningful consultation is well defined in Uganda’s law.  The law on Community Development Framework Agreements is less explicit in Tanzania, provides for local government authorities to participate and approve the negotiations.

4. Land compensation in Uganda and Kenya is negotiated and determined by mutual agreement or market rates while in Tanzania the government plays a major role in determination and payout of compensation. 

5. There are differences in Royalty sharing structures, with Uganda, Kenya and Rwanda providing an extensive royalty retention scheme starting at community to national level. In Uganda the land owner, lawful or Bonafide occupant is entitled to 5% share of the royalty.  In Tanzania the royalty is 100% collected by the Central government via the Mining Commission and directly channeled to the Consolidated fund.

6. There are differences in Value addition, beneficiation and trading provisions. Tanzania, Uganda, Rwanda have mandatory requirements for beneficiation. In Burundi this requirement can be waived, while Kenya’s regulatory regime does not require mandatory value addition, beneficiation. Exportation of raw minerals is allowed.

7. The study further reveals differences and gaps in the regulatory approach to transparency and anti-corruption measures. While Tanzania has a dedicated TEITA Act in place, the other 4 member states have no similar comparative law yet. Uganda has a dedicated Anti-Corruption provision in its mining law (Sect 283), making Uganda the only Country in the EAC with such an explicit provision. The mining law clearly prohibits offers, promises, donations, gifts or benefits off all kind to government officials in the mining sector.

8. The regulatory frameworks show variations to dispute resolution and approaches, with some countries channeling appeals to the Minister, commission or board. They contain provisions for corporate dispute resolution settlement, including options for international arbitration but weak on local grievance handling mechanisms. Some have requirements to establish grievance handling mechanisms but no guarantees that settlements reached are satisfactory to the claimant and parties to the dispute. Creates opportunities for local and international arbitration.

9. Rwanda presents one of the strongest examples of mineral traceability and investment facilitation in the region and its critical-minerals approach is set across several policy framework.

10. Burundi’s 2023 reforms demonstrate increasing efforts to strengthen state participation and local beneficiation, however, the country has not yet adopted a dedicated critical minerals strategy.

11. Community participation mechanisms remain uneven across the region: Uganda and Kenya provide stronger statutory protections through Community Development Agreements than Rwanda and Burundi, where benefits are channeled mainly through local government and municipal transfers.

Key Recommendations

  1. The relevant Ministry of Minerals must develop proper Strategic Plans to govern critical minerals. An embedded approach to governance of critical minerals within the existing regulatory framework is insufficient as critical minerals have distinct characteristics and contextual aspects which require distinct governance undertaking. The Ministry of minerals in Tanzania must finalise and pass the Tanzania Critical and Strategic Minerals Strategy, clearly including the role of host communities and measures to maximize benefits from the Mining of green transition minerals. Value that should be derived.

2. The Relevant Ministries of Minerals and Departments must initiate processes to update and align existing frameworks to be in synchrony with the contemporary context and future demands of the mining sector. This includes developing tax and fiscal regimes that ensure maximum value is derived from EAC’s mining and critical mineral wealth

3. The EAC parliament (EALA) must harmonise or pass the EAC model mining law to provide guidance to member states when drafting new or updating existing mining regulatory frameworks. In the same respect develop a harmonized position in negotiation of new mining deals in the critical minerals sector with companies and regional players such as China, the US and EU.

4. The relevant Ministries and Departments of mineral must strengthen policy and legal provisions relating to host community participation, consent and compensation measures including rights to enter and benefit from Community Development Framework Agreements. Tanzania and Burundi in particular have significant gaps in this area. This is key and must be timely given that the discovery of critical transition minerals is largely taking place in remote under developed and underserved communities

5. EAC governments must review and strengthen environmental rights and safety standards, human rights due diligence measures in their laws, given that the mining of critical minerals such as graphite generates heavy dust pollution and nickel is water intensive.

6. Strengthen or include explicit Anti-Corruption and Ethical provisions in the mining laws, where they are none existent, so as to mitigate the lacuna for corruption and unethical behavior. This must be followed with punitive measures for corrupt and unethical behaviors in the mining sector.

Comparative Snapshot of Mining Regulatory Regimes in 5 EAC Countries

Dimension

Tanzania

Uganda

Kenya

Rwanda

Burundi

Primary mining law

 2017 Mining Laws and RE 2022

Mining & Minerals Act 2022

Mining Act 2016

Law 072/2024

Mining Code 2023; 2023 and 2025 decree

Dedicated critical-minerals strategy

Yes (2025, draft)

No

No, (14 minerals declared strategic)

Strategic minerals approach set across several policy frameworks

No (strategic-mineral clause only)

Mineral ownership

Vested in the President on behalf of citizens

Vested in the government on behalf of Citizens

Vested in National government in trust of Kenyans

Vested in the state for Rwandans

Vested by the State on behalf of the Citizens

Licensing Regime and allocation of rights

Prospecting Licenses (PL), Primary Mining licence (PML), Mining License (ML) and Special Mining Licenses

Prospecting, Exploration, Retention licence, Large-scale, Medium scale, small scale or an artisanal mining licence

reconnaissance, prospecting, retention, a mining license, and Artisanal mines permit


Exploration, Small, Medium, Large and Mineral trading

Prospecting Authorisation, Exploration/

research permit, large permit, small mine

State free-carried / participation

≥16% free carried; up to 50%

Via UNMC / MDA

10% free equity (NMC)

Negotiated; carried interest possible

≥16%, +5% per renewal

Incentives and exemptions

Yes

Yes

Yes

Yes

Yes

Taxation, Fiscal and Headline royalty (metallic/base)

6% metallic

Set by Minister (gross value)

Per regulations (gross value)

3% base metals (norm value)

4% base metals (ad valorem)

Royalty Sharing structure

100% Nationally collected

70 % Govt, 15% Local Govt, 10% Subcounty/town council, 5% land owner, lawful or Bonafide occupant

10% Community, 20% County, 70% National

10% of Mining revenue spent at community

0.5% of Annual turnover to host Municipalities

Mandatory value addition, beneficiation and trading

Yes (med/large licences)

Promoted; permits required

No (raw export allowed)

Mineral processing requires a dedicated licence; government actively promotes domestic processing and expansion of processing facilities

Yes (prior processing, with waiver)

Local-content threshold

Min. 25% -51% local shareholding

Preference; recruitment/training plans

Hire/train + local sourcing

Preference to Rwandan firms

25%–100% Burundian in defined cases

Community Consultation, Participation, FPIC & Benefit sharing

Not explicit, No Community Development Framework agreements

Yes, Mandatory, Consultation defined, right to sign Community Development Agreements

Yes, Mandatory, right to sign Community Development Agreements

Yes, but through local district dev’t plans

Local development plan required, but no mandatory Community Development Agreement framework

Land Rights and Compensation

Market rate, Govt determined

Market rate, Negotiation and Govt as advisory

landowner or lawful occupier entitled to fair compensatio

Provides for fair compensation

Customary and statutory land tenure coexist; implementation and compensation challenges remain

Environmental and Human rights safeguards

Yes, Mining commission with powers to enforce.

Yes, Mandatory for content for MDA and CDA

Yes

Yes, with stringent penalties

Yes, well-articulated, weak implementation

Transparency / anti-corruption and Ethical Conduct

TEITA Act 2015; EITI Membership

EITI, no transparency law, Has Anti-Corruption provision in law

Reforms ongoing, No stand-alone provisions, reliant on the national anti-corruption law

iTSCi; traceability, Anti-corruption spilt btn mining law & standalone Anti-corruption law.

iTSCi , Traceability fees; limited disclosure, No ethical conduct chapters in the law,   Relies on national penal and anti-corruption legislation.

Dispute resolution and grievance handling provisions

Mining Commission may handle disputes (Sect 119), no provision for local or international arbitration, no provisions for local grievance handling mechanisms 

Yes, Mandatory awareness of dispute resolution mechanisms, local govt authorities as facilitators,

Yes, including opportunities for local arbitration and mediation

No stand-alone statutory provisions in the law

Explicit provisions on dispute settlement, limited community grievance

Note: Summary matrix compiled from the country chapters in the main report. Entries are indicative; consult each country chapter and the cited primary sources for exact provisions and current figures.

For more about this study and full report contact us via: www.gepc.or.tz email: info@gepc.or.tz

[1] https://www.eac.int/environment/terrestrial-ecosystems/mineral-resources

[2] URT: Ministry of Energy Budget Speech, 2024/25

[3] https://www.unep.org/news-and-stories/story/what-are-energy-transition-minerals-and-how-can-they-unlock-clean-energy-age

[4] https://goodelectronics.org/climate-change-impacts-of-graphite-production/
Responsible Business Conduct in Tanzania’s Transition Minerals: An Analysis of Policy and Legal Gaps

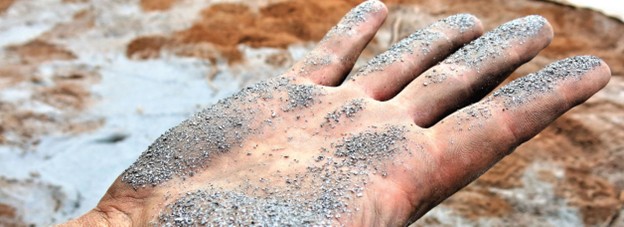
Photo credits: Jumbo Graphite, Lindi

Authors: Moses Kulaba, Don Malish and Stephano Alloys, Governance and Economic Policy Centre

  1. Global Context: Transition Minerals

The global demand for critical minerals essential for the production of batteries, electric vehicles, and renewable energy technologies currently projected to grow dramatically as the world pursues net-zero ambitions. The International Energy Agency (IEA) estimates that demand for critical minerals could increase sixfold by 2050, with their market value set to reach approximately USD 400 billion. An estimated 3 billion tons of critical minerals will be required by 2050 to drive the green transition.

The International Energy Agency (IEA) indicates the demand for critical minerals to achieve the net-zero goals of the Paris Agreement could increase sixfold by 2050, with their value reaching about USD400 billion[1].  To drive the transition to renewable energies, it is estimated that about 3 billion tons of critical minerals will be needed by 2050[2] and this will require an increase in mining activity to supply these quantities.

The IEA Sustainable Development Scenarios [SDS], show the share of total demand for transition minerals will rise significantly over the next two decades to over 40% for copper and rare earth elements, nickel and cobalt (60-70%), and almost 90% for lithium.[3] Further estimates indicate that production of minerals such as graphite, lithium, and cobalt will increase by nearly 500% by 2050, and demand for copper will surge and remain high for a long time.

 The global energy transition and the corresponding surging demand for transition minerals offer opportunities for host nations through increased investment and mineral export revenue. However, the United Nations (UN), the Organization for Economic Cooperation and Development (OECD), and the African Union (AU) have all noted with concern that the increase in demand and mining of transition minerals has the potential to exacerbate economic injustice and human rights risks in mineral-rich countries and mining communities

Mining and processing transition minerals risk damaging landscapes, degrading biodiversity, and fueling greenhouse emissions and human rights abuses. For example, extracting just one ton of lithium consumes about 2 million liters of water, with nearly half of global copper and lithium production occurring in water-stressed regions. There are further concerns that competition for these resources could worsen existing tensions and escalate mineral-driven conflicts in countries and mining communities.

Weak policies and institutions in mineral-rich nations exacerbate such risks, rendering it imperative to navigate the transition minerals sector without adverse repercussions on human rights.

  1. Tanzanian Context

Tanzania hosts globally significant reserves of transition minerals, including graphite, nickel, cobalt, and lithium, positioning it as a potential key global supplier. The mineral resource range from precious metals (gold, silver, PGE), critical minerals (graphite, nickel, cobalt, lithium, niobium, neodymium, praseodymium, vanadium, titanium, tin), and energy minerals (uranium, coal, and helium gas). Tanzania is among the top five largest graphite reserves in the world. (Ministry of Minerals, 2024).

The government aims to accelerate transition minerals exploration, targeting 50% national coverage by 2030. Currently, ongoing transition minerals projects include the Tembo, Dutwa, and Ngwena nickel sites; the Panda Hill niobium site; the Ngualla rare earth site; and the Uranex, Mahenge, Lindi Jumbo, Chilalo, and Epanko graphite sites.

The government is developing a Critical Mineral Strategy to regulate and guide investment, aiming to accelerate exploration to 50% national coverage by 2030. These minerals are essential for the production of batteries, electric vehicles, and renewable energy technologies. Tanzania continues to attract interest from key global mining players.

On the other hand, the government is seeking efficient ways to unlock and maximize the benefits of critical mineral resources, mindful that, in the past, the sector was marred by economic, tax, and human rights injustices.

  1. Why This Matters

 Over the last decade, the government has undertaken several policy and legal reforms to improve the sector with the aim of addressing the above concerns. There are still significant governance gaps, particularly in relation to business conduct and human rights. Tanzania’s drive for a sustainable mining future is a unique opportunity to embed Responsible Business Conduct and Human Rights Due Diligence into mineral policies, as the global demand for transition minerals increases.

At the national level, Tanzania has established multiple frameworks to govern the mining sector, including the Mineral Policy 2009, Mining Act 2010, Permanent Sovereignty Act 2017, Natural Wealth and Resource Contracts Act 2017, Local Content Policy and Regulations 2018, National Environmental Policy 2021, and Environmental Impact Assessment Regulations 2005. The government is also developing the CMS to guide regulation and investment in transition minerals. Mining is recognized as a key economic pillar in the National Development Plans, and the National Development Vision 2050 positions the sector as one of the major economic pillars for driving Tanzania to become a middle-income country.

Despite these frameworks, there are salient gaps from an RBC perspective that need to be addressed. For instance, the government has not yet developed a comprehensive national framework for the implementation of RBC and HRDD in company operations. Moreover, Tanzania’s efforts to attract large‑scale mining through generous incentives and simplified procedures risks weakening HRDD and RBC. The global demand for transition minerals also heightens the risks of conflict, corruption, and environmental harm, underscoring the need for strong policies and governance to ensure the country fully benefits from its mineral wealth.

  1. Study Objectives

The main goal of this study was to encourage policy dialogue and involvement from civil society in promoting Responsible Business Conduct (RBC) and protecting human rights within Tanzania’s transition minerals sub-sector.

The analysis reviewed key policy frameworks, including the Mineral Policy of 2009, the Mining Act of 2010 (revised in 2022), the EITI Act of 2015, and the draft Critical Minerals Strategy (CMS). It evaluated their relevance to the sector’s transition, identifies gaps in RBC, and highlights opportunities for policy improvement.

 The specific objectives were to:

  1. Contextualize Tanzania’s development of critical mineral resources from an RBC and energy transition perspective.
  2. Conduct an RBC gap analysis of the four selected policies and legal frameworks, aiming to identify gaps and opportunities to strengthen HRDD and RBC.

This is analysis was conducted by Governance and Economic Policy Centre (GEPC) with the support of HakiRasilimali as part of the ‘Supporting a Just Transition through Responsible Business Conduct in Africa 2024-2027’ project, made possible thanks to support from the Swedish International Development Cooperation Agency (SIDA). The project aimed to support a fair and inclusive transition in Africa’s extractive sector, thereby promoting responsible business conduct, local community engagement, and sustainable development practices. The full study report of the study is available at GEPC and Hakirasilimali

Key Findings:

The study identified significant governance gaps in the analyzed frameworks, particularly in relation to Responsible Business Conduct (RBC) and Human Rights Due Diligence (HRDD).

  1. Draft Critical and Strategic Minerals Strategy 2025

The Strategy forms an economic governance road-map to position Tanzania as a global critical mineral supplier.

The draft strategy does not establish remedy mechanisms for communities adversely affected by critical mineral operations, offering insufficient clarity on how human rights or environmental harms will be addressed.

  • While it makes broad references to ESG (Environmental, Social, and Governance) principles, it fails to integrate internationally recognized frameworks like the UNGPs or OECD Due Diligence Guidance, and does not mandate companies to implement or report on HRDD practices.

2. Tanzania’s Mineral Policy 2009

The policy is the overarching framework for the mining sector, currently set for review.

  • The policy recognizes the importance of engagement but overlooks the key principles of consultation and engagement, such as Free, Prior, and Informed Consent (FPIC), creating concerns about alignment with international human rights standards.
  • It acknowledges socioeconomic, environmental, and community participation rights but does not explicitly require companies to operationalize RBC or HRDD.
  • It fails to address the rights of Indigenous communities, despite Tanzania’s endorsement of international instruments.
  • It is vague on addressing HRDD, focusing mainly on government monitoring of safety and environmental protection, but stops short of legally demanding that companies conduct or report on comprehensive HRDD processes.
  • The policy includes specific provisions for compensation, relocation, and environmental rehabilitation. However, lacks specific provisions for non-judicial grievance handling, falling short of Pillar III of the UNGPs on effective remedy.

3. Tanzania’s Mining Act 2010 (CAP 123 RE 2019)

This is the overarching law governing the mining sector and matters relating to prospecting for minerals, mining, processing and dealing in minerals, granting, renewal and termination of mineral rights, payment of royalties, fees and other charges, and any other relevant matters. Over the past 10 years, the mining law has undergone significant reviews and amendments, particularly to strengthen government participation in the mining sector. The government plans to review the existing law(s) to ensure alignment with emerging geo-economic developments and the newly formed Tanzania Development Vision 2050.

The Mining Act acknowledge human rights by addressing land rights, relocation, resettlement, and fair compensation, and by requiring community participation and consent before mining companies can access land. It grants various mineral rights, such as prospecting, retention, primary, and special mining licenses under Section 7, and safeguards community land rights through provisions like Section 95, which mandates village council approval and lawful occupier consent.

However, there is no explicit requirement that all mining sector decisions and operations comply with international human rights standards would ensure that the revised law balances economic interests with the protection of communities and their rights.

  1. Conclusion and Recommendations

The study concluded that Tanzania needs to move beyond procedural safeguards and embed Responsible Business Conduct and Human Rights Due Diligence at the core of its policy and legal frameworks to ensure a just and sustainable future. Key recommendations include:

Ministry of Minerals:

  • Integrate Responsible Business Conduct (RBC) and Human Rights in Strategy & Policy: Ensure that the finalization of the Critical Minerals Strategy incorporates RBC and human rights considerations, and that insights from this analytical review informs the development of the upcoming Mining Policy.
  • Strengthen Licensing Conditions: Integrate environmental, social, and governance (ESG) benchmarks into mineral licensing, making compliance a prerequisite for exploration and production rights.
  • Develop Transparency Portal: Build centralized digital platform for public access to contracts, production data, revenue flows, and disclosure reports, ensuring accountability across the sector.
  • Integrate Gender Equity in Mining: Compel mining companies to adopt gender‑responsive policies and mandatory reporting on gender inclusion.
  • Monitoring & Enforcement Capacity: Develop and equip specialized compliance unit within the Ministry to audit disclosures, monitor ESG performance, and sanction non‑compliance.

Parliament of Tanzania

  • Legislate Mandatory ESG Reporting: Pass amendments to the mining law that enforces disclosure of human rights, gender equity, and environmental impacts, harmonized with existing global standards (e.g., OECD, EU).
  • Strengthen Oversight Roles: Empower parliamentary committees to audit mineral revenues, monitor state‑owned enterprises, and further review compliance with established disclosure standards.
  • Improve Community Participation: put in place mandatory provisions requiring free, prior, and informed consent (FPIC) for affected communities in critical minerals projects, embedding social license into law.
  • Amend and strengthen the Extractive Industries Transparency and Accountability (TEITA) Act to mandate full contract disclosure and human rights disclosures.

Tanzania Extractive Industries Transparency Initiative (TEITI) Committee

  • The TEITA Committee should apply its powers under Section 10(2)(a) and (k) to push for human rights disclosures across the mining sector, including within state-owned enterprises and joint ventures in critical minerals.
  • Establish community-level multi-stakeholder structures that replicate TEITI’s national committee model. This would expand transparency and accountability by involving host communities, civil society, and local governments directly in monitoring extractive operations and revenue flows.
  1. Mining Companies (Private and State-Owned Enterprises, including STAMICO)
  • Mining companies should adopt comprehensive human rights due diligence (HRDD) frameworks to align with established global standards.
  • Companies should regularly publish non‑financial reports that disclose their performance on human rights, gender inclusion, and environmental sustainability, which would be subject to independent verification to enhance credibility.
  • Companies should operationalize community grievance mechanisms at the project level operational level

Local Government Authorities

  • Institutionalize effective stakeholders’ engagement including FPIC processes in land acquisition, resettlement, and compensation.
  • Local authorities should be trained and resourced to oversee negotiations, safeguard the rights of vulnerable groups (indigenous peoples, women, youth, persons with disabilities), and ensure equitable benefit-sharing agreements.

Commission for Human Rights and Good Governance (CHRAGG)

  • Strengthen its role in monitoring mining-related human rights violations and handling community grievances. CHRAGG should be empowered with resources and legal authority to ensure timely remedies, independent investigations, and enforcement of sanctions for corporate or state non-compliance.
  • CHRAGG should further strengthen its legislative review mandate by actively recommending reforms to ensure that legal and regulatory frameworks governing the extractive sector are fully aligned with human rights principles and Responsible Business Conduct (RBC) standards.

Civil Society and Media

  • Scale up capacity-building on Responsible Business Conduct (RBC) and HRDD frameworks (UNGPs, OECD, AMV, AU Green Minerals Strategy) for communities in critical minerals zones.
  • Civil society and media should work to document, monitor, and report abuses, while supporting communities in accessing legal aid, remedies, and negotiation processes.
  • Civil society organizations (CSOs) should provide technical support, knowledge, and practical tools to enable businesses and government institutions to effectively implement Responsible Business Conduct (RBC).
  1. Conclusion

Tanzania’s mineral wealth is a once-in-a-generation opportunity. However, without strong communication and enforcement of RBC safeguards, the country risks repeating past mistakes of human, ecological and tax injustices.

If managed responsibly, it can:

  1. Drive industrial transformation.
  2. Attract responsible investment.
  3. Empower communities and protect rights.
  4. Position Tanzania as a global leader in sustainable mining.

[1] https://www.iea.org/news/clean-energy-demand-for-critical-minerals-set-to-soar-as-the-world-pursues-net-zero-goals

[2] https://www.unep.org/topics/energy/renewable-energy/critical-energy-transition-minerals

[3] https://www.iea.org/reports/the-role-of-critical-minerals-in-clean-energy-transitions/executive-summary

An evaluation of Regional Minerals Certification Mechanisms on Mitigating harm from Critical Minerals: A case of KP, ICGLR, RMI & OECD Certification Mechanisms

Photo Credit: ICGLR
Authors:  Moses Kulaba and Roger Vutsoro, Governance and Economic Policy Centre

Introduction

Decades ago, mineral certification was mooted as a solution to addressing the chronic problems of illegal mining, mineral smuggling and mineral driven conflicts, economic injustices and impunity in mineral rich countries.  To this regard, regional and global mineral certification mechanisms were developed with countries and mining companies required to sign up to these new certification principle and mechanisms. However, decades after, minerals continue to be drivers of conflict and harm in many countries.

As the appetite for Critical or Transitional minerals required for the green and clean energy industrial technology gains gusto momentum, there are concerns that this new mineral dash may exacerbate corruption, conflict and suffering in critical minerals rich countries. Apart from calls to establish regional value chains, there is evidence to suggest that a proper global certification mechanism should be put in place to ensure responsive sourcing of critical minerals and that their extraction does not lead to further harm.

This short analytical study explores the existing   national, regional and global certification mechanisms such as the Kimberly Process, ICGLR, OECD Due diligence measures, Responsible Mining Initiatives in the quagmire of improving of minerals governance. It entangles and assesses the increasing perceptions (based on evidence from countries such as the DRC and Ukraine) that the current certification regime is running dangerously obsolete, not designed for critical minerals and thus needs a review and realignment for new purpose, including proposing measures that go beyond the current regional certification.

The brief makes recommendations for the review and expansion of the current existing certification mechanisms. It is relevant and targets stakeholders such as the ICGLR and the Kimberly Process Secretariate, EAC & ICGLR member states, African Union Minerals Development Centre, UNOSEGLR, UN Critical Minerals High Level Panel and the UN SG and civil society organisations interested in stopping human rights abuse illegal smuggling and trading of blood and conflict critical mineral minerals.

What is mineral certification

Mineral certification is a process that verifies the origin and legitimacy of minerals, ensuring they are not associated with conflict or human rights abuses. It involves tracing minerals from the mine site to the final point of export and confirming they are free from illegal activities. This helps to prevent the financing of armed groups and other illicit activities linked to mineral extraction. This certification involves a thorough verification process to trace the minerals’ origin and verify they are free from illegal financing, armed group involvement, and human rights abuses.

At face value, this sounds like a good measure, however existing mechanisms of a similar nature such as the Kimberly process, ICGLR certification initiative and the OECD Due diligence measures have not succeeded in fully addressing the issue of conflict minerals and mineral smuggling. In Countries such as the Democratic Republic of Congo and Mozambique, minerals continue to be a driver of conflict and mineral smuggling to neighboring countries is still rife.  This therefore puts to question the efficacy of the existing global certification mechanism in strengthening governance, regulating supply, improving ethical mining business conduct and reducing harm from extractive resources.

Existing major Regional and Global Mineral Certification regimes

1. The Kimberly Process Certification System (KPCS)

The Kimberly Process (KPCS) is a global standard certification process established in 2003 by the United Nations General Assembly (Under resolution 55/56) to prevent conflict diamonds from entering the mainstream diamond market.  KPCS was set up to ensure that diamonds as precious minerals are sourced and traded in a responsible manner, reducing financing conflicts and human rights violation.

KPCS has laid out requirements for participating member countries to comply including[1] enforcement of regulatory standards to control export and import of rough diamonds, principles of transparent practices to ensure integrity of the diamond supply chains, selective trading with only KP certified and compliant members, verification of exports to ensure every traded diamond is accompanied by a conflict free certificate and an obligation for member countries to enforce theses standards. To date 60 participants (representing 86 countries) are signatory members to the Kimberley process and have committed to applying KP principles in the certification of its traded diamonds.

National Level Governance and Implementation of the Kimberly Process; A case of Tanzania

In Tanzania the Kimberly Process Office is situated in the Mining Commission, an Institution within the Ministry of Minerals. This office is responsible for the implementation of the KPCS activities, import and export of rough diamond; the office is under the authority of the Executive Secretary. The Mining Commission works closely with the Tanzania Revenue Authority’s Customs Department, Tanzania Intelligence and Security Service and the Police Force for strengthening internal control. The Kimberley Process Office forms a part of the Mineral Audit and Trade Department, which is under the Director for Mineral Audit and Trade who assists the Executive Secretary in administering the KPCS activities. The office issues Annual reports.

Before the issuance of Kimberley Process Certificate, the exporter of rough diamonds must submit a valid Dealer’s license/Mining license, which allows him to export minerals outside Tanzania. The Dealer’s license indicates full address, type of minerals, the premises and signature of Executive Secretary or a person authorized to sign. The exporter fills the application form which indicates license type, license number, weight, value, source of diamonds to confirm that diamonds are conflict free, place of export and declaration of exporter by putting his/her signature, name and qualification to apply for a certificate and pays to the government USD 100 as an application fee for Kimberley Process certificate. Post to the valuation process, the exporter is required to pay royalty (6% of a value) and inspection fee (1% of value) to the Government.

Any person who contravenes any of the provision in Diamond trading regulation commits an offence and liable:  In case of an individual to imprisonment for a term not exceeding three years or to a fine not exceeding US dollar twenty thousand (US$ 20,000) or to both. In case of body corporate, to a fine not exceeding US dollar one hundred thousand (US$ 100,000), or c. Cancelation of his license and permanently be disqualified from prospecting, mining or dealing in diamond and any other minerals.  Any rough diamonds obtained contrary to the provisions of Diamond trading regulations shall be forfeited in addition to other penalties[1].

The International Conference on Great Lakes Region (ICGLR) Mineral Certification Measures

The ICGLR Certification mechanism was developed to address the persistent of mineral driven conflicts in the Africa Great Lakes region. It aims to create a conducive environment for cooperation among member states while also ensuring the protection and well-being of the people living in the Africa Great Lakes region.

The ICGLR Certificate confirms a mineral shipment is conflict-free and meets the ICGLR’s ethical sourcing standards, ensuring it’s free from illegal influence and responsibly traced from mine to market. This certification involves a thorough verification process to trace the minerals’ origin and verify they are free from illegal financing, armed group involvement, and human rights abuses. It provides buyers with the assurance that the minerals meet ICGLR requirements for transparency, legality, and responsible sourcing, supporting ethical supply chains in the region[1].

Currently the DRC, Uganda, Kenya, Rwanda and Burundi are members to the ICGLR’s certification mechanism. Mineral flows are analyzed via an ICGLR Regional Database, using the data on individual shipments collected and transmitted to the ICGLR by each Member States.  The database is verified annually via ICGLR Third Party Audits. The mechanism is viewed as an important regional standard and tool for enhancing collaboration, transparency, and development in Africa’s Great Lakes region, promoting accountability and encouraging businesses to pursue certification for adherence.  

The OECD Due Diligence Guidance for Responsible Mineral Supply Chain

Requires that company supply chains of all minerals from conflict affected and high-risk areas, must respect human rights and avoid contributing to conflict through their mineral or metal purchasing decisions and practices. Recognizes that trade and investment in natural mineral resources hold great potential for generating income, growth and prosperity, sustaining livelihoods and fostering local development. However, a large share of these resources is located in conflict affected and high-risk areas. In these areas, exploitation of natural mineral resources is significant and may contribute, directly or indirectly, to armed conflict, gross human rights violations and hinder economic and social development[2].

The OECD Due Diligence Guidance is considered as the first example of a collaborative government-backed multi-stakeholder initiative on responsible supply chain management of minerals from conflict-affected areas. Its objective is to help companies respect human rights and avoid contributing to conflict through their mineral sourcing practices[3].

The Guidance is also intended to cultivate transparent mineral supply chains and sustainable corporate engagement in the mineral sector with a view to enabling countries to benefit from their mineral resources and preventing the extraction and trade of minerals from becoming a source of conflict, human rights abuses, and insecurity. With its Supplements on Tin, Tantalum, Tungsten and Gold, the OECD Guidance provides companies with a complete package to source minerals responsibly in order for trade in those minerals to support peace and development and not conflict
[4]

Responsible Minerals Initiative (RMI)


The Responsible Minerals Initiative (RMI) is a voluntary membership body of companies and industry players with a vision to ensure that mineral supply chains contribute positively to social economic development globally. It seeks to promote the common goal of understanding and contributing to mitigating the salient social and environmental impacts of extraction and processing of minerals in supply chains. It leverages partnerships and use of international standards such as the United Nations Guiding Principles on Business and Human Rights or the OECD Due Diligence Guidance as guideposts[5].

Comprised of more than 500 member companies; the Responsible Minerals Initiative is considered one of the most utilized and respected resources for companies from a range of industries addressing responsible mineral sourcing issues in their supply chains. RMI provides companies with tools and resources to make sourcing decisions that improve regulatory compliance and support responsible sourcing of minerals from conflict-affected and high-risk areas. RMI undertakes due diligence, assurance and reporting templates for cobalt, gold, tin, tungsten, tin, tantalum and other minerals.

The Nexus between Critical Minerals, Conflict and Harm

There is a strong connection between the extraction and trade of certain minerals and the exacerbation of armed conflicts and instability in various regions, particularly in developing countries. Globally, critical minerals fueling Green Tech are also fueling conflict[6] Armed groups often exploit the demand for these minerals (like tin, tantalum, tungsten, and gold, collectively known as “conflict minerals”) to fund their operations, including the purchase of weapons[7]. This reliance on minerals to fuel conflict can lead to human rights abuses environmental degradation, and social unrest, hindering sustainable development. 

Critical minerals such as bauxite, manganese cobalt, lithium and uranium have fuelled conflicts in the DRC, Guinea, Niger, Mali, Chad and Central Africa Republic[8] Myanmar has also experienced a post-coup rush for control over its rare earth minerals, while Latin American countries like Chile and Colombia are grappling with how to ensure that their lithium wealth benefits local economies rather than multinational corporations[9].

Critical Minerals and conflict; A case for DRC and Ukraine

Multiple reports produced by UN and Civil society show that the ongoing violence in the DRC is linked to mineral extraction, with rebel insurgents motivated by a desire to extract from the region’s vast cobalt and coltan reserves. Since the onset of the infamous second Congo War in 1998, control over the DRC’s vast mineral resources has fuelled conflict between armed groups and militias. These factions fight over mining territories, using profits from the illegal extraction and smuggling of conflict minerals to finance their operations and purchase weapons. The struggle for control over mineral-rich areas has led to prolonged violence, contributing to the deaths of millions and leaving entire regions destabilized[1]. Through taxation and smuggling of minerals, armed groups are financially benefiting from DRC’s mineral resources. For instance, The UN Group of Experts estimated that armed groups based in Ituri Province generated approximately $140 million USD in 2024, dwarfing the illicit revenue generated by 3Ts[2]. In light of this reality, the abundance of critical minerals offers a potential opportunity for economic wellbeing but the dash for their control and extraction has potential of increasing conflicts in Africa[3]  

Moreover, the extraction and trade of some critical minerals has intensified new geopolitical tensions and reinforced long-standing patterns of exploitation[4] including conflicts. According to Global Witness,  the Trump Ukraine proposed deal in 2025 revealed a connection of critical minerals to the Russia and Ukraine war and how natural resources in Ukraine have become a key bargaining chip in international diplomacy between the US and Russia. In the same perspective, the US and the Democratic Republic of Congo signed a minerals-for-security deal, highlighting the increase role of critical minerals in geopolitics and conflict. These case studies clearly show that  geopolitical interests are too heavy to be counterbalanced by the existing mineral certification regimes alone.

Gaps and why a new regime for mineral certification is required

From the above analysis and case studies, the existing major regional and global mineral certification regimes have significant gaps that necessitate that a new certification regime is developed. Their gaps are diverse but can be categorized as follows:

Narrowness in focus and scope: Existing certification mechanisms such KP are narrow in scope largely target diamonds and were not designed to cover a broader mining sector. The ICGLR covers the 3Ts and gold. The emergency of a wider list of critical minerals adds a new context which the KP and ICGLR certification mechanisms were not designed for.
 
Voluntary mechanisms; The existing mechanisms are largely voluntary and member states companies encouraged to join and comply with the standards. For instance, the 21st meeting of the CIRGL Regional Committee on the fight against the illegal exploitation of natural resources recommended ICGLR Secretariat to compile a comprehensive report on the status of implementation of the six tools of the regional certification mechanism. This report revealed that the Republic of Rwanda has not yet established the traceability chain for gold. Instead, Rwanda controls gold extraction and trade using conventional methods and does not issue ICGLR certificates for gold exports[5].”
 
Limited in geographical and legal scope: For instance, the OECD Due diligence Guidance is largely applicable to companies from OECD member countries but with limited enforcement mechanisms in non-OECD countries. Yet mining companies from non-OECD Countries such as China are emerging as the leading exploiters of Africa’s critical minerals according to WTO reports[6]. from the DRC. Chinese based companies own or operate 80 percent of the critical mineral production in the DRC, much of which is sent to China for processing for export via the global supply chain[7] Moreover the ICGLR is confined to its member states while the RMI covers only its 500 members.
 
Continuous illicit smuggling and trading in conflict minerals despite the presence of current certification mechanisms. For instance, despite its membership to the Kimberley Process (KP) and ICGLR commitments, Tanzania’s diamond sector is reported as facing entrenched governance challenges such as opaque supply chains, smuggling, and minimal community benefits. Tanzania’s diamonds have suffered from environmental concerns, price volatility from synthetics and smuggled diamonds from regional conflicts areas[8].

Moreover, critical minerals including diamonds are smuggled across borders
, transacted in established commercial capitals and hubs such as Kigali, Kampala, Nairobi and Dubai. For instance, a Global Witness investigation report indicates that an international commodities trader bought conflict coltan smuggled from Democratic Republic of Congo (DRC) to Rwanda.[9]  Based on customs documents seen by Global Witness, the investigation revealed that a multibillion-dollar company headquartered in Luxembourg bought 280 tonnes of coltan from Rwanda in 2024.

Despite having limited or no known deposits and operational mines, some countries in East Africa and the Middle East have emerged as leading exporters of critical minerals such as cobalt, lithium and coltan.  Study reports show large volumes of critical minerals transacted via East Africa to foreign markets such as the UAE and China[10].  For instance, in 2025 Kenyan authorities intercepted 10 containers of suspected smuggled copper at the port of Mombasa[11]  These illicitly acquired, smuggled and transacted minerals have found market into the UAE and Western capitals in Switzerland and New York. In 2023 alone, Kenya’s exports of copper to the United Arab Emirates were valued at US$22.27 million. The UAE exports mineral products, including critical minerals, in significant quantities, primarily to Japan, China, and India, despite having little known deposits of these minerals.

Weak in countering new geopolitical interests and ongoing critical minerals driven conflicts in producer countries: The ongoing mineral driven conflicts have already been documented in the cobalt, coltan mineral rich Eastern DRC and elsewhere but the rush for securing access and control of mineral supply chains by global economic and military superpowers is reviving geopolitical interests and may result in new geopolitical conflicts.
 
In the Democratic Republic of Congo (DRC), for instance, since the revision of its mining law in 2018, the country has attracted no responsible Western investors in the mining industry. Meanwhile, China has come to dominate the production of cobalt and copper, primarily mined in the Katanga and Lualaba regions. The recent re-negotiation by the Tshisekedi Administration of the imbalanced minerals-against infrastructure deal signed in 2008 under the Kabila administration between the DRC and China was perceived by China as triggered by the geopolitical influence of United State of America.
 
Aware of the security and economic implications of China’s control over the DRC’s critical minerals supply chain, the United States has signaled its return to the DRC mining sector through the recent acquisition of Australian AVZ Minerals’ assets in the Manono Lithium Project by KoBold Metals. In addition, the U.S. is committed to funding the Lobito Corridor—a strategic railway project essential for transporting critical minerals from the Central African Copperbelt to Western markets.

Through its International Development Finance Corporation (DFC), the U.S. has pledged a $550 million loan to support the Lobito Corridor. This project is considered vital in countering Chinese influence in the region by providing an alternative route for exporting critical minerals. The corridor is viewed as part of the Partnership for Global Infrastructure and Investment, a G7 initiative aimed at competing with China’s growing presence on the continent.

While the Lobito project is designed to challenge Chinese dominance, both Western and Chinese firms will be allowed to use the infrastructure it provides. This dual-access approach raises questions about its strategic value, particularly under a US administration led by President Donald Trump, whose priority is   competition with Beijing. The Lobito Corridor railway could be a physical indicator of the resuscitated geopolitical rivalry and reconvergence of global superpowers on the African continent as a source for critical mineral resources.

Failure to implement due diligence and traceability mechanisms: During the OECD conference on responsible minerals supply chain held in May 2024 in Paris, many Congolese civil society organizations raised concern over the increasing failure in the implementation of due diligence standards in the DRC. CSO mentioned that private sector actors have failed to fully implement supply chain due diligence in alignment with international standards, most notably the OECD Due Diligence Guidance for Responsible Minerals Supply Chains from Conflict-Affected and High-Risk Area. IMPACT added that companies are either turning a blind eye, preferring not to ask questions about the source of their purchases, or have been complicit by over relying on industry schemes despite red flags being raised in  UN Group of Experts reports.

The concern around ITSCI—the sole traceability and due diligence provider for 3Ts in DRC—has been so great that in 2024 it lost its recognition with the Responsible Minerals Initiative (RMI), with RMI noting that important gaps remained in the scheme’s fulfilment of recognition terms. Despite this move, the UN Group of Experts has expressed concern that many private sector actors still rely on the scheme to conduct due diligence without carrying out additional independent quality controls required by international standards[12].

Civil Society Concerns and call for reforms

Because of these gaps civil society organisations have constantly called for a review and development of a new certification mechanism regime, expanded and aligned to emerging context of transition minerals. For instance, at the start of the 2025 KP plenary in Dubai the Civil Society Coalition pointed out the gaps of the KP in addressing the challenges of diamond mining, smuggling and poverty in the Central African Republic[13]

CSO observed that the KP was narrow in focus, limited to diamonds and the imposed conflict diamond embargos had targeted smugglers without protecting the diamond mining communities. The KP does not—and likely will not soon—prevent diamonds from being associated with issues outside the narrow conflict diamond definition, including human rights abuses, violence by public and private security forces, forced labour, and environmental degradation. Rigorous due diligence is essential, yet it remains insufficiently addressed.

Further,  the instance, the KP in Central Africa Republic’s (CAR) experience demonstrated that the sole existence of the certification scheme does not make diamond governance exemplary. Though diamonds share similar governance challenges with other minerals, the Kimberley Process has largely remained isolated from broader dialogues on mineral-related due diligence.
Civil society demanded for the need to bridge the gaps in the KP certification mechanism by inter alia increasing transparency and engagement with mining communities.  CSOs argued thatwithout transparency, the KP will never effectively achieve its mandate of conflict prevention.

Moreover, the existing certification mechanisms are criticized as elitist, disconnected from the community needs and blind to social economic injustices. For example, the KP certification mechanism does not cover the extent to which the mining of the diamond minerals has benefited the communities from where they are sourced. Investigations by the Kimberly Process Civil Society Coalition of mining operations in Sierra Leone, Lesotho, and the Democratic Republic of Congo, reveals the often-ignored consequences of large-scale diamond mining on local communities in African countries[14].

In Tanzania, despite mining diamonds for more than 100 years, Shyinyanga remains amongst the poorest region in the country[15]. The critical minerals rich Eastern DRC provinces of Kasai Oriental, Kasai Central, North and South Kivu are among the poorest and least developed in the world. 

For diamond resources to truly benefit communities, the documentary identifies greater transparency and independent monitoring as key elements to enhance corporate accountability. Mining companies, industry actors and states all have a role to play to protect community rights and improve both mining and sourcing practices[16].

Further, certification mechanisms do not sufficiently cover or protect citizen against state excesses and inspired violence. Yet the very atrocities committed by rebel groups, which led to the KP’s creation in 2003, are now mirrored by certain governments and their security forces. Top ranking government officials and security forces in the Eastern DRC have been accused of being complacent to illicit mineral trade, despite the existence of the ICGLR certification mechanism.

Conclusion

While certification mechanisms such as the Kimberly process were established for a major purpose of controlling blood diamonds over the years, they have played this role to an extent but equally shown inherent gaps and shortcomings. Their limitation in scope, involuntary membership nature and poor implementation is a major limitation. They were set up when diamond was among the top most traded commodity and driver of conflicts in countries such as Angola, Liberia and Siera Leone. With the increasing surge in demand for critical minerals such as Nickel, Cobalt, Coltan, Graphite, Lithium, Tin Tungsten and Rare Earth Elements, the new frontiers mineral driven conflicts have expanded and cannot continue to remain on diamonds.  In the current and future context, it will be untenable for critical minerals to remain outside the purview of mineral certification. For the existing certification mechanisms to be relevant and fitted for the changing context and era of energy of transition, substantive reviews and reforms are required.

Recommendations for future certification mechanisms

1. Expand the KPI and ICGLR certification to cover a broad range of  critical minerals or develop a new commensurate certification measure for critical minerals, with a focus on ethical sourcing, conflict and governance.

2. Pay attention to the ongoing problems in mining such as the environmental concerns in critical minerals mining operations and their contribution to social and ecological harm to communities and countries from where they are sourced.

3. Pay close attention to ongoing issues within critical minerals supply chains, including human rights abuses, armed conflicts, the fair distribution of benefits to local communities, and compliance with national labor laws

4. Review the existing mineral audit standards, blend composition of  audit teams with experts, civil society and community representatives to increase transparency and integrity in certification

5. Require exporting countries to demonstrate significant economic presence of the critical mineral commensurate with export volumes.

6. Impose export embargoes and critical mineral trading sanctions on countries or companies involved in perpetrating smuggling and export of illicitly acquired and conflict critical minerals.

7. Expand the scope of existing certification mechanisms such as the Kimberly process to capture community benefits from diamonds and critical minerals.

8. Demand that membership to regional and global certification and tracking mechanism must be mandatory for all critical minerals producing and exporting countries

9. Countries that produce critical minerals should diversify their investors and pursue win-win partnerships to prevent their territories from becoming geopolitical battlegrounds for superpowers competing for access to these resources in the era of energy transition

10. Enhance public database and reconciliation system for tracking mineral flows from mining, purchases, and exports at various levels of the value chain
 
11. Mineral certification must be complemented with value addition. This approach will facilitate technology transfer, generate more jobs to stimulate economic growth, and reduce susceptibility to conflict and mineral smuggling
 
References

Aikael Etal (2021) Understanding poverty dynamics and vulnerability in Tanzania: 2012–2018 available at https://onlinelibrary.wiley.com/doi/10.1111/rode.12829  accessed on 15 May 2025
Martin A, etal (2014), All that Glitters is not Gold: Dubai, Congo and the illicit trade of critical minerals, Partnership Africa Canada, May 2014
 
Andy Home, After Ukraine deal, US turns its critical minerals gaze to Africa, available at https://www.reuters.com/markets/, accessed on May 22
 
Global Witness (2025) available at https://globalwitness.org/en/press-releases/new-investigation-suggests-eu-trader-traxys-buys-conflict-minerals-from-drc/ accessed on 15 May 2025
 
IMPACT, Actors Must Suspend Sourcing Minerals Financing Armed Groups in Democratic Republic of Congo, available at https://impacttransform.org/, accessed on May 23, 1:46pm
ICGLR, Report on the Status of Implementation of the Six Tools of the ICGLR Regional Initiative on Natural Resources in Member States, P14
ISSD (2018) Green Conflict Minerals; The Fuels of conflict in the transition to a low carbon economy;  available at https://www.iisd.org/story/green-conflict-minerals/ accessed on 15 May 2025
Panzi Foundation available via https://panzifoundation.org/conflict-minerals-and-sexual-violence-in-the-drc/# accessed on 15 May 2025
The African Climate Foundation Report; Geopolitics of Critical Minerals in Renewable Supply Chains  available at https://africanclimatefoundation.org/wp-content/uploads/2022/09/800644-ACF-03_Geopolitics-of-critical-minerals-R_WEB.pdf  accessed on 15 May 2025
The Eastleigh Voice (2025); Police launch investigation into suspected copper smuggling at Mombasa port; available at https://eastleighvoice.co.ke/business/112007/police-probe-suspected-copper-smuggling-at-mombasa-port accessed on 15 May 2025
 
US International Finance Cooperation https://www.dfc.gov/investment-story/strengthening-critical-mineral-supply-chains-countering-chinas-dominance#:~:text=But%20critical%20mineral%20supply%20chains,sent%20to%20China%20for%20processing.
WTO (2024): High demand for energy-related critical minerals creates supply chain pressures; available at https://www.wto.org/english/blogs_e/data_blog_e/blog_dta_10jan24_e.htm#:~:text=Exports,all%20at%206%20per%20cent). Accessed on 15 May 2025
 
Online sources
https://www.oecd.org/investment/mne/49111368.pdf
https://www.responsiblemineralsinitiative.org/
https://www.kpcivilsociety.org/press/beyond-shining-illusions-new-documentary-exposes-the-unspoken-realities-of-diamond-mining-in-african-countries/


[1] Panzi Foundation available via https://panzifoundation.org/conflict-minerals-and-sexual-violence-in-the-drc/# accessed on 15 May 2025
[2] IMPACT, Actors Must Suspend Sourcing Minerals Financing Armed Groups in Democratic Republic of Congo, available at https://impacttransform.org/, accessed on May 23, 1:46pm
[3] The African Climate Foundation Report; Geopolitics of Critical Minerals in Renewable Supply Chains  available at https://africanclimatefoundation.org/wp-content/uploads/2022/09/800644-ACF-03_Geopolitics-of-critical-minerals-R_WEB.pdf  accessed on 15 May 2025
[4] Global Witness; Critical Minerals Fuel Conflicts available via  https://globalwitness.org/en/campaigns/transition-minerals/the-critical-minerals-scramble-how-the-race-for-resources-is-fuelling-conflict-and-inequality/#:~:text=How%20are%20critical%20minerals%20driving,communities%20in%20resource%2Drich%20nations. Accessed on 15 May 2025
[5] ICGLR, Report on the Status of Implementation of the Six Tools of the ICGLR Regional Initiative on Natural Resources in Member States, P14
[6] WTO (2024): High demand for energy-related critical minerals creates supply chain pressures; available at https://www.wto.org/english/blogs_e/data_blog_e/blog_dta_10jan24_e.htm#:~:text=Exports,all%20at%206%20per%20cent). Accessed on 15 May 2025
[7] US International Finance Cooperation https://www.dfc.gov/investment-story/strengthening-critical-mineral-supply-chains-countering-chinas-dominance#:~:text=But%20critical%20mineral%20supply%20chains,sent%20to%20China%20for%20processing.
[8] URT:  Ministry of Minerals, Mining Commission; A Report on implementation of the Kimberly Process Certification Scheme for Tanzania Year 2023
[9]Global Witness (2025) available at https://globalwitness.org/en/press-releases/new-investigation-suggests-eu-trader-traxys-buys-conflict-minerals-from-drc/ accessed on 15 May 2025
[10] Martin A, etal (2014), All that Glitters is not Gold: Dubai, Congo and the illicit trade of critical minerals, Partnership Africa Canada, May 2014
[11] The Eastleigh Voice (2025); Police launch investigation into suspected copper smuggling at Mombasa port; available at https://eastleighvoice.co.ke/business/112007/police-probe-suspected-copper-smuggling-at-mombasa-port accessed on 15 May 2025
[12] IMPACT, Actors Must Suspend Sourcing Minerals Financing Armed Groups in Democratic Republic of Congo, available at https://impacttransform.org/, accessed on May 23, 1:46pm
[13] https://www.kpcivilsociety.org/activity/kimberley-process-lifts-ineffective-embargo-end-of-an-era-for-the-central-african-republic-and-another-clear-signal-that-conflict-diamond-scheme-needs-serious-fixing/
[14] Kimberly Civil Society Coalition (2025); BEYOND SHINING ILLUSIONS: New documentary exposes the unspoken realities of large-scale diamond mining available at https://www.kpcivilsociety.org/press/beyond-shining-illusions-new-documentary-exposes-the-unspoken-realities-of-diamond-mining-in-african-countries/ accessed 15 May 2025
[15] Aikael Etal (2021) Understanding poverty dynamics and vulnerability in Tanzania: 2012–2018 available at https://onlinelibrary.wiley.com/doi/10.1111/rode.12829  accessed on 15 May 2025
[16] ibid

[1]ICGLR; available via https://icglrcertification.com/ accessed 13 May 2025
[2]OECD Report (2016) available via https://www.oecd.org/en/publications/oecd-due-diligence-guidance-for-responsible-supply-chains-of-minerals-from-conflict-affected-and-high-risk-areas_9789264252479-en.html, accessed on 13 May 2025

[3] OECD (2016), OECD Due Diligence Guidance for Responsible Supply Chains of Minerals from Conflict-Affected and High-Risk Areas: Third Edition, OECD Publishing, Paris, https://doi.org/10.1787/9789264252479-en.
[4] ibid
[5] https://www.responsiblemineralsinitiative.org/
[6] https://www.worldpoliticsreview.com/critical-minerals-conflict-eu/
[7] European Commission: Trade and Economic Security, Conflict Minerals regulation available at https://policy.trade.ec.europa.eu/development-and-sustainability/conflict-minerals-regulation_en#:~:text=In%20politically%20unstable%20areas%2C%20armed,mobile%20phones%2C%20cars%20and%20jewellery. Accessed on 15 May 2025
[8] ISSD (2018) Green Conflict Minerals; The Fuels of conflict in the transition to a low carbon economy;  available at https://www.iisd.org/story/green-conflict-minerals/ accessed on 15 May 2025
[9] ibid

[1] The United Republic of Tanzania: Mining Commission; A Report on implementation of the Kimberly Process Certification Scheme for Tanzania Year 2023

[1] https://www.kimberleyprocess.com/about/what-is-kp

An Analysis of the geopolitical gains and risks of EU Strategic Partnerships, Lobito Corridor and Minerals for Security Deals on East and Southern Africa’s Critical Transition Minerals

Photo credit: Atlantic Council

Authors: Moses Kulaba, Governance and Economic Policy Centre and Robert Letsatsi, Botswana Watch Organization

This policy brief is a significant resource in understanding the geopolitics at play of critical minerals and support of advocacy surrounding regional collaborative initiatives for critical minerals and the necessary positionings that the region must take to benefit from these initiatives.

Introduction

This short analytical brief provides an overview of the critical mineral wealth in Eastern and Southern Africa with a particular focus on the strategic gains and risks the geopolitical initiatives such as the EU Strategic Minerals Partnerships, the Lobito Corridor and emerging minerals for security deals offer. It is estimated that the mining industry needs to invest $1.7 trillion over the next 15 years to extract and supply enough metals for renewable energy and Africa possess almost half of these.    The brief discusses the geostrategic posture of superpowers such as the US, Europe, Russia and China in the context of the dash for control of critical minerals for the green transition and the current extractive governance challenges facing the region. While strategic alliances may not entirely be a bad idea, the brief highlights the geopolitical, security and perceived neocolonial undertones that may come with these initiatives. And how the historical socio-economic justice concerns of similar geopolitical jostling, security guarantees at the Berlin conference and hinterland to port initiatives contributed to the exploitation of Africa’s resources for benefits elsewhere. The brief further highlights on the possible benefits that the region can garner from these initiatives and measures the region can take so as to avert the risks and maximise benefits from these partnerships.

This policy brief is a significant resource in understanding the geopolitics at play of critical minerals and support of advocacy surrounding regional collaborative initiatives for critical minerals and the necessary positionings that the region must take to benefit from these initiatives.

Background

The surging demand for minerals critical to green transition offers potential economic benefits for mineral rich countries however the dash to secure their supply chain has kicked off geopolitical interests, competition and realignments whose outcomes could have long lasting relationship with divergent unforeseen impacts. With the Eastern and Southern Africa combined as a single economic bloc, the region has the highest concentration of critical green transition minerals such as cobalt, coltan, nickel, graphite, tungsten, tantalum, copper in the world. Yet the history of governance and management of the mineral sector has never yielded very positive dividends for mineral-rich countries in the region. Minerals have fueled conflicts in the DRC and Mozambique, Debt traps in Zambia, political patronage and environmental concerns in Zimbabwe and economic inequalities in South Africa and Botswana.

So far, the EU has signed Critical Minerals Strategic Partnerships with 5 Africa green minerals rich countries and the US led Lobito Mineral Corridor partnership plan to connect the Democratic Republic Congo’s mineral rich Katanga region and Zambia with a railway line to the Angolan Port of Lobito.  Moreover, in recent years we have witnessed the emergence of Minerals for Security deals signed between the US and Ukraine and the US with the DRC and Rwanda.  These developments offer a new geopolitical twist in this global race to secure the critical green transition minerals, pitting the developed western economic superpowers against China in the dash for Africa’s critical mineral resources. Amidst this mineral dash and geopolitical balkanization, it is feared that without strategic positioning, the Eastern and Southern Africa critical minerals rich countries could again miss out from this mineral boom.

Overview of Critical Minerals in Eastern and Southern Africa

Critical Minerals in East Africa

East Africa is vastly endowed with critical minerals with Tanzania having the 5th largest graphite reserves globally (18million tons) and 1.52 million tons of high-grade nickel (URT: Madini). With the DRC combined, the East Africa accounts for more than 50% of Africa’s critical minerals output of graphite, copper, cobalt, coltan and nickel. For instance, the DRC holds the world’s largest cobalt reserves, accounting for about 70% global output and ranks as Africa’s largest and the world’s second-largest copper producer.  The recent discoveries of coltan in Kenya also further adds to the EAC’s critical minerals deposits size.

Despite this potential, EAC as a block has not yet maximized benefits from its mineral wealth.  Member states have been working on competing policies to improve governance, attract ethical investments and increase local beneficiation. The DRC government is working on policies to improve governance, local beneficiation, and attract ethical investment to reduce dependency on Chinese processing yet its neighbors are equally setting mineral refineries to perform the same functions.

Mineral Resources in EAC

CountryPrecious metal, Gemstones & Semi-Precious MetalMetallic MineralsIndustrial minerals
BurundiGoldTin, Nickel, copper, cobalt, niobium, coltan, vanadium, tungstenPhosphate, Peat
KenyaGemstones, goldLead, zircon, iron, titaniumSoda ash, flour spar, salt, mica, chaum, oil, coal, diatomite, gypsum, meers, kaolin, rear earth
RwandaGold, gemstonesTin, tungsten, tantalum, niobium, columbiumpozzolana
TanzaniaGold, diamond, gemstones, silver, PGMsNickel, bauxite, copper, cobalt, uranium, graphiteCoal, phosphate, gypsum, pozzolana, soda ash, gas
UgandaGold, diamondCopper, tin, lead, nickel, cobalt, tungsten, uranium, niobium, tantalum, ironGypsum, kaolin, salt, vermiculite, pozzolana, marble, soapstone, rear earth, oil

Source: EAC Vision 2050 and South Sudan Development Strategy

Critical Minerals in Southern Africa

Southern Africa holds vast deposits of the world’s critical minerals. For example, South Africa holds the largest (90%) reserves of Platinum Group Minerals (PGMs) globally (Critical Minerals and Metals Strategy South Africa 2025). South Africa and Zimbabwe account for 92% of global reserves of PGM and produced 82% of platinum globally in 2022 (UNCTAD: 2023).  Zambia has large Copper deposits accounting for 70% of Africa’s exports while Zimbabwe has the largest lithium reserves globally (estimated at 11 metric tons in Masvingo Province). Lesotho, Botswana, Namibia and Angola have some of the largest deposits of diamond. Angola has been diversifying beyond oil and diamonds, promoting critical minerals exploration and processing. The government is enhancing mining regulations, attracting foreign investment, and seeking strategic partnerships to develop local value chains. As one of the world’s top ten largest copper producers, Zambia is strengthening policies to boost value addition, encourage local smelting and refining, and attract Western investment. Zambia is Africa’s second-largest copper producer after Democratic Republic of Congo and the country is positioning itself as a major supplier in clean energy and EV industries.

From the above data, the Eastern and Southern Africa combined accounts for more than half of the global supply of critical minerals such as copper, coltan, platinum, graphite, manganese, nickel and lithium. In recent years there has been an increasing focus towards critical minerals with global mining exploration budgets for minerals such as lithium, copper and nickel rapidly spiking up since 2022.  This places the East and Southern Africa region at the heart of competing geopolitical interest in race for the control of critical minerals supply chains. In the midst of this rush, the Eastern and Southern Africa region countries have been competing amongst themselves and undercutting each other to attract key large-scale players in the mining sector. This race has both socio-economic, human rights and geopolitical risks and concerns.

What are the key socio-economic justice concerns in the mining sector

The history of mining in the region has not been perfect. Like in previous mining experiences generally, increased extraction of critical minerals raises serious key socio-economic justice concerns like environmental injustice, gross violation of human rights, climate change, community displacement and land grabbing, lack of transparency and accountability, corruption and unequal distribution of benefits. Such concerns have been put in even greater spotlight, where demand for these minerals worldwide began to rise and will surge over the next 20 years in support of the energy transition and technological advancements.

Mining of critical minerals is happening in new land frontiers never explored or exposed to large scale mining before. This contributes to significant environment impacts around villages and communities where they are found. Their effects range from land rights violations via new evictions to destruction of social infrastructures such as schools, hospitals and residential homes due to blasting for minerals (BHRT: 2025). Land degradation, dust pollution and loss of arable agricultural land through clearances for new mines affects health and livelihoods. Processing of minerals such as Lithium and Nickel requires a lot of water and this is contributing to water shortages and pollution of water sources around the mining communities[1].   

Courtesy photo credit: Graphite mining site preparation by Jumbo Graphite Company in , Lindi, Tanzania

Moreover, critical minerals are driving existing and new conflicts in many African countries such as the DRC, Rwanda, Burundi and Mozambique. According to UN reports, the desire to control exploitation of critical minerals are a major driver for the ongoing conflict in DRC[2].

Geopolitics of Critical Minerals

The increasing demand and competition for critical minerals is driving unending geopolitical tensions over which countries can gain access to these resources and how best to manage them. Critical minerals geopolitical competition amongst global economic superpowers; China, US, EU, Russia, United Kingdom and new emerging powers such as Australia, UAE and India have increased in recent years. A raft of strategic partnerships and infrastructure partnerships such as the Lobito corridor have been signed.  Recently, we have witnessed the emergence of ‘Mineral for Security deals’ such as the ones signed between the US- Ukraine and the US- DRC aimed at transferring control of portions of critical mineral supplies in exchange for security guarantees and protection. There are many geopolitical interests and used tools at play but these are the noticeable physical manifestations of this geopolitical competition for critical minerals that is evolving across Africa.

The potential benefits and consequences of these new geopolitical realignments are diverse but alignments and signed deals effectively force smaller and poor countries to surrender sovereignty of their mineral natural resources by attaching their political interest and survival to the supply of critical minerals to the stronger states or regional economic power centers.

Moreover, there has been a surge in the use of counter friendshoring measures by importing countries establishing direct partnerships with exporting countries for raw critical minerals. While this may be viewed as a positive development for minerals and commodities trade, the tilted partnerships reinforce the underdevelopment of the downstream supply chain capacity for critical minerals, especially as developed countries secure the Just Energy Transition (JET) technologies. And are not willing yet to transfer this technology to the minerals source countries. The complex dynamics and intricate geopolitical forces surrounding critical minerals therefore demands a comprehensive and forward-thinking strategy to effectively navigate the evolving global landscape[3]. Without this, the risk of securing little benefits from the critical mineral wealth for Eastern and Southern Africa is real.

The EU Strategic Minerals Partnerships and implications on Africa’s critical Minerals

Amid global geopolitical tensions, the EU has been ramping up efforts to diversify its mineral value chains. The EU has forged strategic partnerships with critical minerals resource-rich African nations like Tanzania, Namibia, DRC, Zambia and Rwanda. To date the EU has established partnerships for critical raw materials with at least 14 countries [4]. These nitty-gritties of these partnerships are widely known to the public and citizens of the mineral rich countries but the EU states they are designed to secure access to critical minerals at various stages of the value chain, strengthen European industrial resilience and accelerate the green transition of its economies while supporting Africa’s own industrialization ambitions. The EU has further established a multistakeholder partnership with the US to develop the Lobito corridor project[5]. While these partnerships are considered vital in ensuring improved mineral governance and securing investment inflows into Africa’s mining sector, on the flipside they are viewed controversially as a strategic path for the EU’s footstep into the Critical Minerals arena and its continued dominance by tightly tying Africa as a source of raw critical materials to feed Europe’s industrial base.

According to the EU, the strategic partnerships will involve cooperation on supply chain integration, infrastructure financing, research and innovation, capacity building, and sustainable sourcing of minerals. The EU strategic minerals partnerships therefore have a prospect of placing Africa as a global player in the critical minerals space and potentially securing Africa’s positive contribution towards a net zero future.

Africa does not have an establish strong industrial base to consume all its critical minerals wealth and therefore foreign investment and partnerships like these is important. With strategic leverage and tactful negotiation, Africa can potentially wean itself off the largely exploitative contracts previously signed with mining companies that were economically biased, had disregard for human rights and responsible sourcing. Without tearing the existing contracts apart, Africa can establish a new progressive framework to guide its mining.

However, the EU mineral partnerships are viewed as inherently biased and pursued with less consideration of transparency, socio-economic and environmental considerations. The terms of these partnerships are not widely known to the public and citizens where they are signed. The EU has not been keen and proactive in promoting the contents of these partnerships . By pursuing this silent approach, the EU risks falling into the widely criticized opaque foreign policy relations trajectory taken by other players such as China.

According to SOMO, the EU strategic partnerships are perceived as not good for addressing climate change and net zero. Despite the green tint, the EU is focused on the minerals and less on the effects. Europe is ultimately pursuing a resource-intensive growth strategy to bolster its industries in profiting from low-emission technologies. This prioritization of growth neglects that affluent countries’ overconsumption of resources is the root cause of climate change and the major driver of biodiversity loss, pollution, and waste. Worse, the unfavorable trade regimes [secured under the partnerships] can prevent poor resource-rich countries from climbing up the global value chains[6].

For the EU strategic partnerships to be beneficial and widely supported, they have to be structured differently if compared to other Critical Minerals Resource deals which are considered lopsided, exploitative and largely promoting the hinterland to port resource extractive infrastructural legacy. The EU critical minerals partnerships will have to, as a must, adhere to principles of transparency, equity, promote creation of value, reduction of human and environmental rights and conflicts in the countries and communities where these minerals are exploited.

The Lobito Corridor Initiative and its implications

The Lobito Corridor is a 1 300 km rail and infrastructure project stretching from the Angolan port of Lobito to mining regions of Kolwezi in the Democratic Republic of the Congo (DRC) and Zambia. Financed by the US and its EU allies, the project provides an alternative route to transport minerals such as cobalt and copper, helping to diversify mineral supply chains in the region. According to the US Department for Finance Corporation (DFC), the Lobito corridor initiative is not just any traditional development aid project but a strategic initiative aimed at strengthening critical mineral supply chains by countering China’s dominance[7]

Justification for the Lobito Corridor Project

According to the US Department for Finance Corporation (DFC) the Lobito Corridor project is poised to spur trade, industrialization, and regional integration across Southern Africa. The advanced technologies required for the industries of the future depend on reliable access to copper and cobalt. These minerals are essential for batteries, wind farms, electric vehicles, as well as energy transmission and distribution.

But critical mineral supply chains are threatened by Chinese dominance. Companies based in China own or operate as much as 80 percent of the critical mineral production in the Democratic Republic of the Congo (DRC), much of which is sent to China for processing. And China is pushing new projects to further secure its dominance, adding to the estimated $1 trillion it has spent on its global infrastructure initiative known as its Belt and Road Initiative, or BRI. 

Additionally, many of the world’s most mineral-rich countries such as the DRC lack the infrastructure to transport growing volumes of these materials to major coastal ports where they can be exported to markets around the world. DRC is the second-largest global producer of copper, and the largest producer of cobalt with a 70 percent global market share[8].

Key gains from Lobito Corridor Initiative

Offers an opportunity of revitalizing defunct infrastructure in a region severely affected by war. A railway built more than 100 years ago connecting mining sites in the DRC to the Lobito port in Angola was largely destroyed during the Angolan civil war. A reconstructed railway suffered from poor construction and upkeep. As a result, these critical minerals are currently transported by heavy-duty trucks to ports in South Africa and Tanzania over roads that can take months to travel. Growing demand for critical minerals threatens to exacerbate the problem. Analysts predict that cobalt demand will exceed the pace of production before the end of 2024 and thereby justifying the construction of new infrastructure projects such as the Lobito Corridor project[9].

The Lobito corridor project provides an opportunity for opening up new investments into the region.  According to the initial plans the US Finance Cooperation would provide a $553 million loan to the Lobito Atlantic Railway to finance the upgrade and rehabilitation of more than 800 miles (1,300 km) of the rail connecting the city of Luau on the border of the DRC to the port city of Lobito in Angola, as well as the upgrade and rehabilitation of the mineral port in Lobito.

The investment is intended to improve the cost-effectiveness, speed, and resilience of global supply chains by upgrading and rehabilitating the railway in Angola that increases the efficiency and reliability of transportation out of the DRC’s mines. And it ensures China will not secure a monopoly on critical minerals access and transit routes in this key region.  

Over the last decade, China had subsidized new construction and upgrades to rail systems in the region, including in Angola, DFC’s neighbor to the west and home to several key coastal transportation hubs, such as the Port of Lobito and the Benguela Railway that extends eastward from it into the DRC. Chinese companies and China-linked entities have worked to control regional transportation systems and restrict access to U.S. and allied businesses, creating challenges to investments in markets like the DRC. However, those projects have suffered from what The Wall Street Journal described as “poor construction and upkeep,” leading to “rundown stations, malfunctioning safety systems offline servers and frequent derailments on the train line.”

According to the US, the DFC’s investment will diversify away from Chinese-controlled economic corridors. It will reinforce railway tracks and bridges along the route and add containers, trains, and equipment such as mobile cranes and forklifts. These investments are expected to increase Lobito’s transportation capacity from 0.4 million metric tons per year as of the end of 2024 to 4.6 million metric tons. It will also benefit the local economy, where minerals make up 90 percent of the DRC’s total exports, accounting for 40 percent of its GDP and $30 billion in value as of last year.

Lobito and projects like will bolster trade access in and around Angola. The coordination led by DFC—which is poised to expand to new projects— presents a boom for U.S. industries, with Angolan organizations already looking to source equipment from the United States for mining, storage, and other integral elements of the project. 

More broadly, the Lobito project strengthens Angola’s role as a key security and economic partner of the United States and as a leader in Sub-Saharan Africa working to resolve issues—including those that affect American interests such as the peace process in eastern DRC. Angolan President João Lourenço also recently assumed the role of chairman of the African Union, and the Lobito project is considered as a potential lever for influencing positions and securing other strategic projects across Africa.  

Graphic highlighting 30% reduction in shipping cost and 29-day reduction in shipping time as a result of DFC’s investment in the Lobito Atlantic Railway

Source: US International Finance Corporation

According to the DFC, within Angola, the project will upgrade critical infrastructure to international standards and will ensure that access to rail remains open to all paying customers. It is expected to generate significant local income there, with total local procurement of goods and services expected to reach more than $350 million within the first five years.  

And it is expected to create more than 1,000 new full-time jobs for Angolans, growing the existing workforce from 434 to more than 1,500. Other support projects will benefit from the investments in the Lobito Corridor.   For example, a $10 million loan from DFC to Seba Foods Zambia Ltd. is designed to support the expansion of its food production and storage capacity for maize-based, soya-based, and other nutritious and affordable consumer food products, strengthening the food value chain in Zambia, which is on the eastern end of the Lobito Corridor. Seba Foods was the first U.S. Government-financed food security and agribusiness-focused investment following the announcement of the vision for the Lobito Corridor. 

The Lobito Corridor initiative exemplifies the competition, with the US and EU aligning efforts to establish stronger supply chains. China, already investing heavily, aims to enhance its Belt and Road Initiative along the corridor. The US has indicated that China can still utilize the railway for its exports. The US-China cooperation on this project may create new avenues for sustainable development in Africa. If the two superpowers align their Lobito strategies, it could accelerate Africa’s green industrialization. Jointly-driven investments would align with Africa’s broader economic growth and sustainable development goals. Africa’s potential for growth will attract both powers, as both seek competitive positions within the Lobito Corridor. China has already recently signed a $1 billion deal to restore the TAZARA railway[10].

Key concerns of the Lobito Corridor Initiative

The Lobito Corridor project exemplifies the geopolitical interests to serve the US and EU interests rather than Africa (Zambia Angola & DRC’s) interests. As clearly stated by the US and the EU, the Lobito corridor initiative is intended to strategically increase the US and EU’s dominance and security of access to Africa’s critical minerals supply chains and diversifying Africa away from Chinese-controlled economic corridors. This project is therefore largely driven by external interests and Africa finds itself in the middle of these competing geopolitical interests.

The project exacerbates the colonial hinterland to port extractive infrastructure, designed with a major purpose of extracting and transporting Africa’s resources as raw materials from the hinterland to the port ready for export to benefit elsewhere. The Lobito initiative railway project has no interconnection with other transport nodes to facilitate in country mobility and connectivity to other economic sectors. It is therefore designed with an exploitative lens driven with an ‘extract and take away’ mindset, with less beneficial considerations to the broader national public concerns. Financing of arteries linking the railway to other transport infrastructures would address significant infrastructure problems affecting millions of people across the countries in the corridor. For example, an East-West railway connection could link Lobito and TAZARA routes, creating Africa’s first transcontinental railway. Such a corridor could bridge the Atlantic and Indian ocean[11].

The project will be financed with loans acquired from the US and EU, whose payment will be recouped from revenues from the operations and sale of the critical minerals. This is ironical as the lenders will be the major beneficiaries from the mineral export. The long-term net effect or benefit from these may be negligible as the debt burden for the corridor countries (Angola, DRC and Zambia) will increase and they may be forced to pay using their minerals resources.

The strategic partnerships and Lobito corridor project have no plans to invest in critical minerals value addition with in the participating countries. As a consequence, the project may consolidate Africa’s exclusion from the critical minerals global value chain, locking Africa to lower tier of the value chain as a supplier of critical raw materials.   Current studies and evidence show that Africa integration in the Global Value Chain is largely through forward linkages whereby it primarily provides unprocessed raw materials to feed the industrial development and economic prosperity elsewhere.

For example , the United States Geological Survey (USGS) and UNCTAD data shows that the DRC and Zambia refine only about 7% and 3.5% of all the copper produced, which is far much lower than their share in the global production.[12] In recent years China has emerged as the leading processor of critical minerals (Lithium, Copper, Nickel & Cobalt) implying that Africa’s minerals are exported raw, processed and re-exported back to Africa as intermediary or finished goods.

Moreover, the Lobito corridor does not promote intra Africa trade in minerals and therefore runs contrary to Africa’s mineral and economic development ambitions as articulated in the various propositions of the Africa Unions Agenda 2063 and the Africa Mining Vision particularly in regards to regional cooperation and beneficiation. The USGS report for 2023 shows that African Minerals are largely traded with countries outside Africa. For instance, the DRC accounts for 77% of Africa’s cobalt exports, however, its intra Africa links are few. This suggests its trade is largely more with countries outside the continent. Several countries with insignificant cobalt reserves and production re-export more beneficiated cobalt through regional networks as indicated in the table below, reaping bigger economic benefits from added value. 

Table showing Africa Major Critical Minerals Export Destination, Intra Africa Trade and Linkages

Africa Critical MineralTop Five Global Export DestinationsAfrica trading partnersIntra Africa trade shareImplication
CobaltChina (72%), Belgium (2%), Malaysia (2%), Switzerland (2%)Zambia, Namibia, Morocco, Congo, Madagascar, South Africa, DR Congo, Mali, Tanzania, Mozambique, Uganda, and Kenya.South Africa (1%), DRC (89% to Zambia, Namibia and Morocco), Congo (4.4%), Zambia (3.5%)The top five global destinations consume 80% of Africa’s cobalt   More of DRC’s cobalt is re-exported by other countries.
GraphiteChina (28%), Germany (15%), India (9%), USA (7%) and Malaysia (7%)Nigeria, South Africa, Swaziland, Niger, Guinea, Tanzania, Madagascar, Zimbabwe, Ethiopia, Sudan, Namibia, Tunisia, Morocco, Senegal, Mozambique, Cameroon, Egypt, 30 Algeria, Côte d’Ivoire, Kenya, Mauritius, Ghana, Botswana, Libya, Sierra Leone, Equatorial Guinea, and Mali.South Africa (51%), Tanzania (14%), Seychelle (12%), Kenya & Morocco (3%).The top five global destinations account for 64% of Africa’s Graphite export   These countries export to fewer African countries. Tanzania only has eight intra-Africa graphite export links (Angola, South Africa, Mozambique, Zambia, DR Congo, Burundi, Comoros and Madagascar, while Seychelles has one (South Africa)
LithiumFrance (7%), USA (5%), Russia (1%) Germany & China (2%)36 African CountriesDRC (77%), South Africa (15%), Morocco (1%), Tanzania (1%)The top five consume 15% of Africa total lithium exports from at 36 countries   DRC has the lowest intra exports links to Africa while South Africa, Kenya and Morrocco lead in number of intra Africa export links.
ManaganeseChina (58%), India (10%), Norway (5%), Japan (4%), and Russia (3%)31 African CountriesMorocco (42%), Zambia (11%), South Africa (20%), Ghana (1%)These countries account for about 80% of Africa’s Manganese exports outside Africa.   Morocco, South Africa, and Zambia (in consecutive order) emerge as countries with the highest intra-Africa export shares for Manganese.   South Africa and Kenya have the highest intra-Africa export links.
Platinum Group of Metals (PGM)United Kingdom accounting for about 28%, Japan 17%, Belgium about 15%, United States of America 12% and Germany 9%.45 CountriesZimbabwe (86%), Ghana and DRC (3%),These countries account for about 89% of Africa’s PGM export outside the region   South Africa has the highest intra-Africa export links to thirteen countries, followed by Swaziland and Malawi

In the long run, the Lobito corridor project will potentially weaken further existing limited intra Africa linkages and collaborative projects by setting up or creating an unfavorable competition for already existing infrastructure such as the Tanzania-Zambia Railway (TAZARA) and the Ports of Dar es Salaam, Beira in Mozambique and Durban, which have recently received major uplifts with costly loans from China and other global financial institutions such as the World Bank.

The Lobito Corridor project excludes itself from other major problems facing mining in the region, including addressing previous economic injustices and human rights related issues, the long-term effects of war and climate change. Because of the fear of being edged out by China, the Lobito corridor project does not come with stringent requirements and expectation for adherence to high human rights standards by the partner countries.

Mineral for Security Deals and implications on Africa’s critical minerals.

Amidst the ongoing geopolitical interest for critical minerals, recently we have witnessed the emergence of Minerals for Security Guarantee deals as a tool for control of access to critical minerals supply chains. On 30th April 2025 the US signed a Minerals for security deal with Ukraine and in June, the US signed a similar Mineral for Security deal with the DRC and Rwanda. The deals provide access to critical minerals in return for security guarantees from the US. Although the deals have been covered with a peace and conflict resolution imperative, they are perceived as essentially aimed at securing the US’s access to critical minerals. In multiple speeches, President Trump has been categorical that these deals must secure critical minerals for the US and thereby amplifying the nexus between geopolitics, Africa’s critical minerals and conflicts.

According to Global witness, the deals like the extraction and trade of some critical minerals intensify new geopolitical tensions, reinforcing long-standing patterns of exploitation[13] including conflicts. For instance the Trump-Ukraine deal revealed a connection of critical minerals to the Russia and Ukraine war and how critical mineral natural resources in Ukraine have become a key bargaining chip in international diplomacy between the US and Russia.

In fact, the government of the Democratic Republic of Congo reached out to the Donald Trump administration with a Ukrainian-style proposal in February 2025 in response to the rapid advance of the M23 rebel group in the east of the country. At stake are the mineral riches of North and South Kivu provinces, a major but highly problematic source of metals such as tin, tungsten and coltan[14].

According to different sources, this deal was presented as a pacification tool for eastern DRC as it could stop the advance of belligerent forces in the region but equally boost Rwanda’s processing of Congo minerals while providing the US with an assured source of processed critical minerals required to support its industrial technology and security needs.

The full contents of deal are not readily available to the public but leaked versions mentioned requirements for withdrawal of Rwandan Forces from the Eastern DRC and integration of the M23 belligerent factions into the DRC’s forces.

Researchers and analysists argue that the mineral deals essentially consolidate a firm grip of the US on access to DRC’s critical minerals, closing off competition against other potential rival countries such as China and Russia, there by exacerbating grounds for economic injustice, opacity, lack of transparency and potential for unfair mining deals, biased in favour of the security guarantors.

Mineral deals are tainted with opacity, designed with a biased exploitative and a neocolonial mindset aimed at rewarding the dominant superpower and the aggressor against the victim. They are negotiated behind closed doors and their full terms are not availed neither to the public nor the citizens of the mineral rich country.

According to Kambale Musavuli of the Centre for Research on Congo-Kinshasa, the US brokered deal between the DRC and Rwanda is wild. The US is getting access to $2 trillion of worth of DRC minerals in exchange for forcing the withdrawal of M23 militias. That is one tenth of the DRC’s total mineral wealth, more than any single foreign country claims. This is strange because analysts of the region have long argued that the US effectively enabled foreign support for the M23 in order to destabilise the DRC, prevent a functional state from arising and achieving sovereignty over its mineral wealth, and thus ensure minerals stay cheaply available for US firms. If this analysis is correct then the US acquired $2 trillion mineral rights in exchange for stopping a conflict that it has effectively supported. Consider also how media discourse is playing out. Remember that in 2008 Chinese firms signed a deal with the DRC to obtain $9billion in minerals in exchange for infrastructure development. Western media went wild with narratives of “Chinese colonisation”. Now the US has secured minerals deal 200x larger and the media narrative is all about how the US brings “peace”

The mining security deals were negotiated in secrecy led by political elites and diplomats. As such citizens are disempowered from having a say in the future management of a vital sector, whose benefits are signed off to another country by a few, dashing hopes for citizens stake into a better future.

The minimum threshold of minerals signed off in the form of US mining companies investing in the critical minerals sector is not clear and whether the DRC has any stake at what percentage in the minerals extracted by the US companies is largely unknown.

Natural resource policies have a contagion effect. The deals potentially open up a can of worms for future similar deals, covering natural resources such as forestry, wild life management and critical infrastructure such as ports, airports, water ways and food supply chains.

Moreover, the deals may not be a permanent solution to ongoing conflicts. The mineral for security deals largely covers security guarantees against ‘external aggression’ and may not be fitted for dealing with internal political and socio-economic drivers for conflict such as historical injustices, land and citizenship rights, regional economic imbalances, bad governance and banditry. Local insurgent rebel groups and militias may continue to pursue their political and economic ends outside the ambits of the security deal. For example, on the very day that the US-DRC and Rwanda deal was signed, one of the rebel groups, Codeco militia attacked and killed at least 10 people at a displaced people’s camp in Ituri province.  There are more than 100 rebel groups in Eastern DRC. The M23 which was largely mentioned in the US deal has already described it as a tiny part’ of a solution to the conflict.

Further, the security guarantees provided under the deal are not clear. It is not clear what these mean and when and how such guarantees can be deployed. For instance, does security guarantee mean supply of arms or armed mercenaries, military intervention or alliances with US soldiers fighting alongside or against the aggressor. Moreover, it is not clear whether the US can be directly involved in fighting internal rebel groups and insurgents without triggering nationalistic and constitutional challenges, driving internal political conflicts further.

By nature, deals of this nature are long term and cannot easily be breached without consequences. The terms and consequences for such breach are less known to the public. The conditions for termination or renegotiation are equally not known.  Therefore, the mineral security agreement essentially locks countries towards dealing with one major economic superpower whose primary interest is access to the country’s critical mineral wealth.

Conclusion

The EU strategic partnerships, the mineral security guarantee deals and the Lobito project may entirely not be a bad idea, however their implicit risks cast shadows about their potential in advancing Africa’s critical minerals and economic development goals. The key concerns around these strategic mineral alliances and the Lobito Corrido are embedded within the broader critical development discourse and concerns about decolonization and recolonization, sovereignty, security and resource nationalism, state capture, perpetration of socio-economic injustices by dominant global capital and Africa’s wealth transfer. Specific concerns include risks for increasing mineral bad governance and economic injustices and vulnerabilities, geopolitical tension, and the need to pursue sustainable mining practices.

With these strategic partnerships, mineral for security deals and the Lobito railway in place, these critical rich countries are locked into long-term commitments to ensure the supply of metals. The major question constantly paused is how can Africa relate as an equal partner with other powers in the race for critical minerals without surrendering its critical minerals wealth to the full benefit of others elsewhere. Moreover, over dependence on certain countries can pose risks when such countries face political instability or become embroiled in geopolitical disputes drawing in Africa’s mineral rich countries in their midst. For these alliances to be mutually beneficial, they must ensure that the resources are accessed equitably, that benefits are fairly distributed, and that environmental impacts are kept to a minimum for their sustainability in the long run .

Recommendations
  1. The strategic partnerships must go beyond critical minerals exploitation but venture into addressing broader social economic development concerns of the people in the mineral rich countries.
  2. The Lobito Corridor initiative must avoid the ‘hinterland to port’ colonial legacy by establishing railway transport interconnection nodes to other existing railway infrastructure so as to improve connectivity across the project countries to ease the bigger infrastructure challenges that these countries face.
  3. The strategic partnership and Lobito Corridor must encourage value addition by investing in processing and exporting of value-added products, so as to generate wealth at source.
  4. Africa Mineral rich countries must explore and establish south to south partnerships, thereby increasing their leverage and power to negotiate with external partners and mining companies
  5. The EU strategic partnerships and the Lobito Corridor project must not exacerbate the role of minerals as drivers of conflict by supporting and buying minerals from conflict zones.
  6. Moreover, these alliances must ensure that the resources are accessed equitably, that benefits are fairly distributed, and that environmental impacts are kept to a minimum for their sustainability in the long run.
  7. The Minerals for security deals must be transparent and not biased exclusively in favour of the dominant economic super power.
  8. The Minerals for Security deals must avoid advancing human rights abuses by US mining companies under the US government protection
  9.  The strategic partnerships, security deals and their associated projects must promote national dialogues and citizens participation in governance of critical minerals and mitigation of harm from mining
Selected References

Andreoni et al., (2023) Critical Minerals and routes to diversification in Africa: Linkages, pulling dynamics and Opportunities in medium-high tech supply chains; Backup paper commissioned by the UNCTAD Secretariate for the 2023 edition of the Economic Development in Africa Reports

Andy Home, After Ukraine deal, US turns its critical minerals gaze to Africa, available at https://www.reuters.com/markets/, accessed on May 22

EITI; Using Transparence Benefits EU Mineral Partnerships; Accessed via https://eiti.org/blog-post/using-transparency-benefit-eus-mineral-partnerships

Global Witness; Critical Minerals Fuel Conflicts available via  https://globalwitness.org/en/campaigns/transition-minerals/the-critical-minerals-scramble-how-the-race-for-resources-is-fuelling-conflict-and-inequality/#:~:text=How%20are%20critical%20minerals%20driving,communities%20in%20resource%2Drich%20nations. Accessed on 15 May 2025

IMPACT, Actors Must Suspend Sourcing Minerals Financing Armed Groups in Democratic Republic of Congo, available at https://impacttransform.org/, accessed on May 23, 1:46pm

Railway Supply ; (2024) US-China Lobito Corridor Investments Drive Africa’s Economic and Sustainable Growth;  https://www.railway.supply/en/us-china-lobito-corridor-investments-drive-africas-economic-and-sustainable-growth/

Somo; The EU Critical Minerals Crusade (2024) ; accessed via: https://www.somo.nl/the-eus-critical-minerals-crusade/

US International Finance Cooperation https://www.dfc.gov/investment-story/strengthening-critical-mineral-supply-chains-countering-chinas-dominance#:~:text=But%20critical%20mineral%20supply%20chains,sent%20to%20China%20for%20processing.

URT: Madini accessed via: https://www.madini.go.tz/page/e8a4201d-286f-4409-9db0-719311652336/

[1] https://www.gov.za/sites/default/files/gcis_document/202505/critical-minerals-and-metals-strategy-south-africa-2025.pdf


[1] Emerging Human Rights Implications of Transition Minerals Extraction and processing: Case Studies from Democratic Republic of Congo, Mozambique and Zimbabwe

[2] IMPACT, Actors Must Suspend Sourcing Minerals Financing Armed Groups in Democratic Republic of Congo, available at https://impacttransform.org/, accessed on May 23, 1:46pm

[3] ibid

[4] https://eiti.org/blog-post/using-transparency-benefit-eus-mineral-partnerships

[5] https://ecfr.eu/event/critical-minerals-and-eu-africa-strategic-partnerships-where-do-we-stand/

[6] https://www.somo.nl/the-eus-critical-minerals-crusade/

[7] US International Finance Cooperation https://www.dfc.gov/investment-story/strengthening-critical-mineral-supply-chains-countering-chinas-dominance#:~:text=But%20critical%20mineral%20supply%20chains,sent%20to%20China%20for%20processing.

[8] ibid

[9] ibid

[10] https://www.railway.supply/en/us-china-lobito-corridor-investments-drive-africas-economic-and-sustainable-growth/

[11] https://www.railway.supply/en/us-china-lobito-corridor-investments-drive-africas-economic-and-sustainable-growth/

[12] Andreoni et al., (2023) Critical Minerals and routes to diversification in Africa: Linkages, pulling dynamics and Opportunities in medium-high tech supply chains; Backup paper commissioned by the UNCTAD Secretariate for the 2023 edition of the Economic Development in Africa Reports

[13] Global Witness; Critical Minerals Fuel Conflicts available via  https://globalwitness.org/en/campaigns/transition-minerals/the-critical-minerals-scramble-how-the-race-for-resources-is-fuelling-conflict-and-inequality/#:~:text=How%20are%20critical%20minerals%20driving,communities%20in%20resource%2Drich%20nations. Accessed on 15 May 2025

[14] Andy Home, After Ukraine deal, US turns its critical minerals gaze to Africa, available at https://www.reuters.com/markets/, accessed on May 22

How investment treaties impact Tanzania’s mining regulatory policy

Photo credit: Mining Review Africa

Author: Joshua Woodend, Associate Researcher and Analyst, Governance and Economic Policy Centre

Abstract

Tanzania’s mining sector is central to national economic growth, contributing significantly to GDP and employment. However, the country’s reliance on foreign investment has bound its regulatory space to the constraints of international investment treaties. Bilateral investment treaties (BITs), in particular, grant expansive investor protections such as the ‘fair and equitable treatment’ standard, which often allow companies to challenge legislative reforms through costly arbitration. These mechanisms restrict Tanzania’s ability to implement necessary policies, including reforms aimed at increasing tax revenues, enhancing local employment, and addressing social and environmental concerns.

While reforms since 2010 have boosted government revenues and domestic benefits, they have also triggered arbitration claims, with Tanzania already paying over $100 million in related costs. To regain policy autonomy, Tanzania may consider terminating existing treaties, clarifying regulatory frameworks, and developing a model BIT with targeted carve-outs, thereby balancing investment promotion with sovereign control and sustainable development objectives.

Introduction

Tanzania’s mining sector is a major contributor to the nation’s economic development. Over the past decade, the industry has experienced steady growth, with mining projected to contribute 10% of GDP in 2025 (Ministry of Minerals, 2024). This significance is equally reflected in employment trends. A 2018 UNEP study estimated that the artisanal small-scale mining sector employed over a million Tanzanians, and in 2021, large scale mines were recorded to employ 14,742 people, significant figures for a nation of 60 million (Mutagwaba et al, 2018; Ministry of Minerals, 2024).

Tanzania’s mineral wealth has drawn substantial international investment, a trend actively encouraged by the government given the country’s limited capacity to exploit these resources without external capital. Consequently, as with many African nations, the mining industry is inexorably tied to foreign investment and ownership. The nation’s 2023 investment report on foreign private investments demonstrates this as mining and quarrying dominates FDI, being over 3 times larger than the second highest ranking sector, manufacturing (Bank of Tanzania, 2023).

For Tanzania, attracting international investment in the mining sector is a complex balancing act. On the one hand, the government must provide conditions favourable enough to persuade international mining companies to supply the capital needed to stimulate national growth and drive economic development. On the other hand, it is necessary to ensure these terms are not so generous that they undermine the government’s ability to control the mining sector, or that they provide conditions so favourable for foreign mining firms that there is no incentive to protect local people and retain some profits locally. This challenge is clearly reflected in Tanzania’s investment treaty regime.

What are investment treaties?

Investment treaties are agreements that define how a state treats foreign investors within its territory. Their scope is broad, encompassing a range of formats and parameters. Some are bilateral, covering investment flows between two states, such as the treaty between Tanzania and Finland. Others are multilateral, like the General Agreement on Tariffs and Trade (GATT), or regionally focused, such as the African Continental Free Trade Area. At present, Tanzania has 11 bilateral investment treaties in force, 7 treaties with investment provisions, is party to a range of multilateral intergovernmental agreements, and has also entered into an unknown number of privately negotiated investment agreements with large-scale investors (UNCTAD).

Whilst these treaties often succeed in creating favourable conditions for international companies investing in the mining sector, they also limit the government’s power to regulate this sector. This stems from the broad protections such agreements provide and the stringent enforcement mechanisms they enable. In particular, bilateral investment treaties (BITs) are especially known for constraining a nation’s ability to enact legislation changes, an especially contentious issue in Tanzania’s mining sector.

This is because the wording of BIT provisions is notoriously vague, leaving room for extremely broad interpretation. For example, all of Tanzania’s BITs include a provision guaranteeing the ‘fair and equitable treatment’ of investments. Whilst this may appear innocuous, it has often been interpreted to protect a business’s legitimate expectation of a stable regulatory environment. As a result, even necessary changes to the mining industry can breach these treaties, as the regulatory environment is no longer stable. This results in a process known as investment treaty arbitration, a legal mechanism that favours investors over governments, allows companies to bypass domestic legal systems, and, on average, costs respondent states $4.7 million USD in legal fees, before any damages are awarded (Hodgson, Kryvoi, and Hrcka, 2021).

The threat of arbitration, combined with the broad scope of BIT provisions, often enables international mining companies to protest any legislative changes, including those aimed at improving the well-being of local communities. For example, in Foresti v. South Africa (2007), an Italian mining company alleged South Africa had breached the FET clause of the South Africa-Italy BIT by introducing affirmative action legislation that required mining license owners to divest a percentage of shareholdings to historically disadvantaged South Africans (Poulsen, 2015). Whilst this legislation was obviously necessary to reduce apartheid era inequalities, was universally applied and non-discriminatory in its implementation, the FET provision presented a huge legislative hurdle and cost in its implementation.

Since the 1960’s Tanzania has signed a long list of Double Taxation Agreements and Bilateral Investment Treaties with different Countries.  Some of these have since been terminated while a number of these continue in force with their corresponding provisions having relative effect on the mining.

Table 1 – Tanzania’s BITs in force (Excluding Investment Related Instruments)
Tanzania’s BIT Obligations
TreatyDate of SignatureTermination ProtocolKey Provisions Relating to MiningStatus (Active/ terminated/ Renegotiated/  
Canada Tanzania BIT2013Contract is active indefinitely but can be terminated 10 years after signing (2023) with termination becoming effective one year after a notice is given. Select articles shall remain in force for 15 years after termination.Provides carve outs protecting the regulation of exhaustible natural resources provided such measures are not applied arbitrarilyActive
China Tanzania BIT2013Contract is active indefinitely but can be terminated 10 years after signing (2023) with termination becoming effective one year after a notice is given. Select articles shall remain in force for 10 years after termination.Provides carve outs for regulation protecting the environment, provided they are not applied arbitrarily.Active
Turkey Tanzania BIT2011Contract is active indefinitely but can be terminated 10 years after signing (2021) with termination becoming effective one year after a notice is given. Select articles shall remain in force for 10 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Mauritius Tanzania BIT2009Contract is active indefinitely but can be terminated 10 years after signing (2019) with termination becoming effective one year after a notice is given. Select articles shall remain in force for 10 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Switzerland Tanzania BIT2004Contract is active indefinitely but can be terminated 10 years after signing (2014) with termination becoming effective six months after a notice is given. Select articles shall remain in force for 10 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Finland Tanzania BIT2001Contract is active indefinitely but can be terminated 10 years after signing (2011) with termination becoming effective one year after a notice is given. Select articles shall remain in force for 15 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Italy Tanzania BIT2001Contract is active indefinitely but can be terminated 10 years after signing (2011) with termination becoming effective one year after a notice is given. All articles shall remain in force for 20 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Denmark Tanzania BIT1999Contract is active indefinitely but can be terminated 10 years after signing (2009) with termination becoming effective one year after a notice is given. All articles shall remain in force for 10 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Sweden Tanzania BIT1999Contract is active indefinitely but can be terminated 10 years after signing (2009) with termination becoming effective one year after a notice is given. Select articles shall remain in force for 15 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
United Kingdom Tanzania BIT1996Contract is active indefinitely but can be terminated 10 years after signing (2006) with termination becoming effective one year after a notice is given. All articles shall remain in force for 20 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Germany Tanzania BIT1968Contract is active indefinitely but can be terminated 10 years after signing (1978) with termination becoming effective one year after a notice is given. Select articles shall remain in force for 20 years after termination.Whilst the treaty is not explicit on natural resources and mining, it applies to all investment, including mining. FET provisions are included by default and hugely limit domestic capacity to regulate mining.Active
Tanzania’s Treaties with Investment Provisions
TreatyDate of SignatureTermination ProtocolKey Provisions Relating to MiningStatus
African Continental Free Trade Area2018Contract is active indefinitely but can be terminated 5 years after entry into force (2023), with termination becoming effective two years after notice is given. Pending rights and obligations shall continue to apply despite termination.No obligations in the treaty prevents the enforcement of measures related to the importations and exportations of gold or silver, the conservation of exhaustible natural resources or exports of domestic materials necessary to ensure essential quantities of such materials to a domestic processing industry  Active
Trade Agreement Between the East African Community and United States of America2008Contract is active indefinitely but can be terminated at any point after signing, with termination becoming effective 180 days after notice is given. No survival clauses apply.Does not specify mining but is included under its remitActive
South African Development Community Protocol on Finance and Investment2006Contract is active indefinitely but can be terminated at any point, with termination becoming effective 12 months after notice is given. No survival clauses apply.States shall promote the use of their natural resources in a sustainable and an environmentally friendly manner; recognise that it is inappropriate to encourage investment by relaxing domestic health, safety or environmental measures; Nothing in this Annex shall be construed as preventing a State Party from exercising its right to regulate in the public interestActive
East African Community Treaty2000Contract is active indefinitely but can be terminated at any point, with termination becoming effective 12 months after notice is given. No survival clauses apply.Requires integration of environmental management in mining sector and the sustainable use of natural resourcesActive
The Treaty on Southern African Development Community1992Contract is active indefinitely but can be terminated at any point, with termination becoming effective 12 months after notice is given. No survival clauses apply.Mandates member states to cooperate in mining and natural resource sectors for purpose of regional developmentActive
Treaty Establishing the African Economic Community1991Contract is active indefinitely but can be terminated at any point, with termination becoming effective 12 months after notice is given. No survival clauses apply.Requires mutual cooperation on policy around natural resourcesActive
Impacts of Investment treaties on Tanzania’s mining sector regulation

The Tanzanian mining sector has been repeatedly constrained by treaty obligations, facing both threats and actual arbitration proceedings in response to reforms aimed at retaining greater value within the country. Notable measures include the Mining (Value Addition) Regulations of 2020, which require the use of local service providers and processing facilities; the Mining (Local Content) Regulations of 2018, which mandate the employment of Tanzanian nationals; and the Mining Act of 2010, which significantly increased royalty rates.

Whilst all these changes may violate investment treaty provisions, such as the ‘fair and equitable treatment’ standard, due to their radical nature, such efforts for reform are to be expected given the previous unfavourable legislative status quo that disadvantaged Tanzanian people. The scale of this disadvantage is stark: between 1997 and 2005, Tanzania exported over US $2.54 billion worth of gold yet collected merely 10% in tax revenue, a disparity that generated significant social tension (Curtis and Lissu, 2008; Noe, 2006). In 2015 Tanzania instituted significant mining reforms, including changes to the mining fiscal regime, increasing government stake and control of the mining sector.  For comparison, since Tanzania’s mining sector reforms, between 2023/24 alone, Tanzania raised over US $2.5 billion in tax revenue and massively increased the employment of local people (Ministry of Minerals, 2024).  These reforms triggered  investment disputes and led to costly arbitral awards.

Determining the precise financial cost of Tanzania’s mining regulation changes through investment arbitration fees and penalties is challenging. Through ICSID, a widely-used arbitration mechanism, Tanzania had by 2025 already paid over $100 million USD in fees for its legislative changes, specifically for cancelling retention licenses that had granted foreign mining companies pre-emptive rights to specific locations (UNCTAD, 2025).

However, this figure likely represents only a fraction of the total arbitration costs stemming from Tanzania’s mining policy reforms. Many BITs enable arbitration through mechanisms that operate without public disclosure requirements outside of ICSID, meaning the actual financial burden on the Tanzanian government may be substantially higher than publicly reported figures suggest.

Consequently, investment treaties significantly impact Tanzania’s capacity to introduce mining reforms by granting investors broad rights that enable litigation over even minor regulatory changes. The threat of compensation payments, combined with high arbitration costs, at best imposes a substantial financial burden on mining sector reform efforts, and at worst, creates powerful disincentives that discourage the government from proposing or implementing changes that improve local development. This can easily result in a regulatory environment that favours investors and foregoes significant taxation revenue that could benefit the nation at large, including those who are proximate to mining enterprises and it’s damaging effects.

Consequently, investment treaties constrain Tanzania’s capacity to reform its mining sector by granting investors expansive rights that allow them to litigate against even modest regulatory changes. While the immediate impact is the risk of substantial compensation awards and the heavy financial burden of arbitration proceedings, the implications extend further. Bilateral investment treaty provisions can lock in tax concessions or limit fiscal space, resulting in foregone revenues that could otherwise support national development. Equally, non-financial costs emerge: the prospect of diplomatic or political pressure, the withholding of aid, and negative media portrayals of Tanzania as a hostile investment destination. Together, these pressures can deter policymakers from pursuing reforms that prioritise domestic welfare over investor interests. In practice, this often produces a regulatory environment that privileges foreign mining companies at the expense of local communities and the state’s ability to capture taxation revenues.

Policy Recommendations

So, what can Tanzania do to remedy this situation? The most direct step would be to terminate its existing bilateral investment treaties, a move already taken by countries such as Ecuador, Bolivia, South Africa, Indonesia and India (Public Citizen, 2018). Yet this is far from a quick solution. As shown in table one, many of Tanzania’s treaties contain survival clauses that ensures provisions can be in force for up to 20 years after termination, this makes termination a necessary but inevitably long-term measure.

In the meantime, Tanzania must work to reduce perceptions of risk by presenting a clearer and more predictable regulatory environment. While past legal reforms in the mining sector have often appeared erratic, future changes should be grounded in transparent communication with stakeholders and shaped around consistent licensing and tax frameworks. This would build investor trust in the market, despite the lack of BITs, as they can rely on the government to act in rationale, legal manner, with space for negotiation.

Finally, Tanzania may invest in developing its own model BIT, complete with prudential carve-outs that reflect Tanzania’s development priorities. The development of such a treaty would allow the country to reassure investors of fair treatment while avoiding the loss of vital policy space.

Bibliography:

The Bank of Tanzania, The Tanzania Investment Centre and The National Bureau of

Statistics (2023). Tanzania Investment Report 2023 – Foreign Private Investments. Dar

es Salaam: Government of Tanzania.

Curtis, M. and Lissu, T. (2008). How Tanzania is Failing to Benefit from Gold Mining. Dar es Salaam: The Christian Council of Tanzania.

Hodgson, M., Kryvoi, Y. and Hrcka, D. (2021). 2021 Empirical Study: Costs, Damages and Duration in Investor-State Arbitration. London: British Institute of International and Comparative Law, Allen and Ovary.

Ministry of Minerals (2024). Investor’s Guide Tanzania Mining Sector 2024. Dar es Salaam: The Ministry of Minerals, pp.1–23.

Ministry of Minerals (2024). Ministry of Minerals – Republic of Tanzania. [online] Madini.go.tz. Available at: https://www.madini.go.tz/page/03cef72a-bdd3-41dc-ba84-40954095b835/.

Mutagwaba, W., Bosco Tindyebwa, J., Makanta, V., Kaballega, D. and Maeda, G. (2018). Artisanal and small-scale mining in Tanzania – Evidence to inform an ‘action dialogue’. London: International Institute for Environment and Development.

Noe, C. (2020) Graduated Sovereignty and Tanzania’s Mineral Sector. Utafiti. [Online] 14 (2), 257–280.

Poulsen, L. N. S. (2015) Bounded rationality and economic diplomacy: the politics of

investment treaties in developing countries / Lauge N. Skovgaard Poulsen (University

College London). Cambridge: Cambridge University Press.

Public Citizen (2018). Termination of Bilateral Investment Treaties Has Not Negatively

Affected Countries’ Foreign Direct Investment Inflows. Washington D.C: Public Citizen.

The Bank of Tanzania, The Tanzania Investment Centre and The National Bureau of Statistics (2023). Tanzania Investment Report 2023 – Foreign Private Investments. Dar es Salaam: Government of Tanzania.

UNCTAD (2022). The International Investment Treaty Regime and Climate Action | Publications | UNCTAD Investment Policy Hub. [online] Available at: https://investmentpolicy.unctad.org/publications/1269/the-international-investment-treaty-regime-and-climate-action

UNCTAD (2025). Tanzania, United Republic of | Investment Dispute Settlement Navigator  | UNCTAD Investment Policy Hub. [online] Unctad.org. Available at:

https://investmentpolicy.unctad.org/investment-dispute-settlement/country/222/united-republic-of-tanzania  [Accessed 17 September 2025].
Webinar Invitation: Assessment of Legal and Policy Regulation of Mining and Critical Minerals in East Africa

As the global energy transition accelerates, the strategic value of East Africa’s mineral wealth—from lithium and cobalt to rare earth elements—cannot be understated and increasingly under spotlight . However, the true bridge between resource wealth and sustainable development lies in robust, transparent, and harmonized legal frameworks.  As the world demands more critical minerals for the energy transition, the legal and policy frameworks governing these assets across East Africa are undergoing massive transformations. Navigating these shifting regulations is vital for investors, policymakers, and communities alike.

This webinar will provide an overview Assessment of the current legal regulatory terrain governing mining in selected East Africa Community (EAC) Countries with a particular focus on mining regulatory framework in Tanzania, Kenya, Uganda, Rwanda and Burundi. It highlights the critical mineral potential, policy and legal framework governing the allocation of mining rights, taxation and fiscal regime, exemptions and incentives, local content provisions, land compensation and environmental regulations, Artisanal and Small Mining (ASM), Minerals Value Addition and Trading. The findings from our short studies suggest that despite the developments in legal reforms over the last decade, progressive movement on critical minerals regulation and safeguards of environmental, community rights and responsible business conduct has remained varied across countries and stagnant. Our panel of experts will unpack the complex legal, policy, and ESG frameworks that will dictate how these resources are managed, traded, and governed.

Our Experts Panel to dissect this topic will be: 

  •  Dr. Ange Dorine Irakoze, a premier Legal & Policy Expert from Burundi, who will share insights on domestic statutory updates.
  • Mr Robert Tumwesigye,  National Coordinator, Resource Justice Network Uganda, a veteran Natural Resource Governance Specialist from Uganda, focusing on state participation and ESG compliance.
  • Eng. Benjamin Mchwampaka,  Executive Director, Tanzania Chamber of Minerals, Representing the private sector perspective
  • Eng. Emmanuel Makotanyi Munyali, Geologist and Natural Resources Specialist, DRC
  • Moses Kulaba, Executive Director and Moderator, Governance and Economic Policy Centre (GEPC)

Date: Wednesday, August 26 · 11:00am – 12:30pm

Time zone: Africa/Nairobi

Google Meet joining info and Video call link: https://meet.google.com/hrs-ugrh-imd

Assessing the Impact of the EU’s Carbon Border Tax Adjustment Mechanism on Tanzania’s LNG and fossil-based exports


Author: Lulu O’lang (Phd), Researcher and consultant, Governance and Economic Policy Center

Executive Summary:

The European Union’s (EU) proposed Carbon Border Tax Adjustment Mechanism (CBAM) aims to mitigate carbon leakage by imposing a carbon tax on imports of certain commodities that are not taxed internally within the exporter’s country at a comparable level. This policy brief evaluates the potential impact of the CBAM on Tanzania’s promising liquefied natural gas (LNG) project and fossil-based exports. It offers strategic recommendations for mitigating adverse effects and enhancing Tanzania’s export competitiveness.

Background:

Tanzania has large deposits of natural gas and the government is actively seeking attract investment to develop this massive resource for both domestic and export markets. Part of this plan includes gas to power projects by pumping natural gas into the national grid for power generation and export of Liquefied Natural Gas (LNG) to foreign markets. Efforts are underway to construct a massive LNG project in the Southern part of the Country. Tanzania is pushing to sign the host government agreement for its $42 billion Tanzania LNG project by mid-2026, a deal led by Equinor and Shell that would unlock one of Africa’s largest gas developments and set the country on a path to become an LNG exporter[1]. However, this comes at time when the global fossil energy markets and industries are constantly evolving and facing unpredictable future due to efforts to combat global warming by reducing or transiting away from fossil-based energy sources. The global regulatory framework for energy markets is changing, with higher expectations of companies to reduce their carbon foot prints. The EU market will significantly change with the introduction of new European Union generalized measures to reduce incentives of EU based firms to outsource their carbon emission to other Countries outside by imposing taxes or limiting importation of fossil-based products from non-EU countries.

 What is EU Carbon Border Adjustment Mechanism (CBAM)

The EU Carbon Border Adjustment Mechanism (CBAM) is the EU’s landmark tool to prevent carbon leakage and support the EU’s increased climate ambitions. It works by putting a price on carbon emitted during the production of carbon-intensive goods entering the EU to incentivize cleaner industrial production in non-EU countries.  

Carbon leakage refers to the process of shifted production and/or emissions to other jurisdictions with less stringent emission constraints. It is one of the key obstacles for the EU to reach its climate commitments. The CBAM was designed to specifically address this risk. Carbon leakage can occur when a domestic carbon price negatively impacts the competitiveness of an entity operating in this domestic context. This increased cost might result in the entity shifting its production to another country with a lower carbon price to reduce production costs. For example, a steel producer might consider relocating its production outside of the EU to avoid paying for the carbon it emits. Another possible instance of carbon leakage occurs when non-domestic producers that are not subject to the price of carbon enjoy significant competitive advantages compared to domestic producers, resulting in a shift of production abroad[2]. The CBAM is also intended to promote more environmentally friendly production methods in third countries.

How it will work


Illustration Source: Let Me Ship
As it stands, the implementation of the CBAM will have far-reaching implications for fossil export countries worldwide.  Countries with reliance on fossil exports or fossil-based exports will be significantly affected.

Some early studies indicate that CBAM will disproportionately impact some non-EU economies because many of the potentially impacted economies have a low capacity to adapt their productive structure to shift to less-emitting industries or to adopt low-emission cutting-edge technologies (Magacho et al., 2024). New fossil producing countries such as Tanzania will potentially be more impacted by CBAM. Hence, these countries need to take more action to ensure that the negative impacts are significantly minimised. CBAM will equally impact costs and availability of fossil based goods and services in the EU markets as these have to pay an additional surcharge to compensate for their carbon footprints in the EU (Sabyrbekov & Overland, 2024).

Policymakers on both sides of this initiative must carefully consider a multitude of factors, including its impact on EU trade, its potential effects on the well-being of domestic populations, the influence it might have on public opinion, and broader economic relations with the EU.

Goods covered under CBAM

The CBAM will initially only be applied to goods with a high potential for carbon leakage: Aluminum, iron, steel, fertiliser, electricity, hydrogen and cement. The CBAM takes into account both greenhouse gas emissions that occur directly in the production of products and indirect emissions that arise from the manufacture of intermediate products or the electricity required for production.3 

Both certain intermediate products and some downstream products such as liquefied natural gas, petrol, heating oil, synthetic rubber, plastics, lubricants, antifreeze, fertilisers and pesticides are affected. It is expected that all products that are also subject to intra-European emissions trading will be added in the coming years[3]. Effectively, from 1st January 2026, only authorised CBAM declarants will be able to import the corresponding goods. 

General Effects of CBAMs of Carbon-based exports

The effects of the Carbon Border Adjustment Mechanisms include:2

  • The import of these goods becomes more expensive due to the pricing of CO2 costs.
  • Potential additional revenues from CO2 pricing of imports are to be invested in climate protection.
  • Incentive for other countries to introduce CO2 pricing so that they can continue to trade freely with the EU.

Tanzania’s LNG and Fossil Exports

Tanzania has large deposits of natural gas which are currently estimated at 57 Tcf. Tanzania is on the verge of leveraging its significant natural gas reserves through a Liquified Natural Gas (LNG) project expected to substantially boost exports, particularly to the world market.

The project is led by Equinor of Norway and Shell, joined by ExxonMobil, Pavilion Energy, Medco Energi and the state-owned Tanzania Petroleum Development Corporation. The development targets more than 47 trillion cubic feet of offshore natural gas, turning it into exports by cooling the gas into liquid form for shipment. First production is around 2034 and this, if completed will, this project will be the largest in East and Southern Africa, creating jobs and earning Tanzania significant revenues. For Tanzania, LNG is a chance to convert its undersea buried gas resource into revenue, jobs and energy.

However, the project arrives as the world debates the future of fossil fuels. Demand for gas is strong now but clouded over the long run. Supporters argue gas is a bridge fuel that can power growth with lower emissions than coal. Critics warn of stranded assets if demand fades. Tanzania bets that buyers will want its gas for decades to come[4] and global market regulatory frameworks will friendly,

Potential Impact on Tanzania’s LNG and fossil-based exports

The LNG is not being directly targeted in the first phase of CBAM as the EU’s CBAM will in the first phase target iron & steel and aluminum and in its next phase cover cement, fertilisers, electricity, and hydrogen.  

The potential challenge to Tanzania’s LNG is primarily through the overall impact of CBAMs on natural gas export markets and industrial production from gas fired electricity, since natural gas could be considered as a significant fossil input into final industrial products exported to the EU.  Moreover, EU’s influence on global trade norms and expectations regarding carbon emissions could significantly affect on global energy companies seeking to invest into Tanzania’s LNG. For long, negotiations between the companies and government stalled over taxes and guarantees.

Competitiveness: The main issue that most developing countries are concerned about CBAM is the competitiveness of their products (Magacho et al., 2024; Perdana et al., 2024). Despite the initial phase of CBAM not directly affecting LNG, the trend towards global carbon pricing mechanisms may influence the competitiveness of Tanzania’s LNG. The naturally low CO2 content of Tanzanian gas, however, positions it favorably against competitors, potentially offering a competitive edge in a carbon-sensitive market.

Market Access: Tanzania’s LNG market is predominantly Asian countries, data shows that the export of Intermediate goods, food and vegetables dominates the export products to the EU. There is no clear plan for exporting LNG to the EU however should the plan include it in its expansion plan, the CBAM could set precedents affecting market access for energy exports by encouraging stricter carbon intensity benchmarks in the EU.

Tanzania’s current carbon trading framework underlines its readiness to engage in carbon reduction initiatives, which could facilitate smoother market access. However, the means to determine the carbon content/ carbon accounting system of traded commodities crucial  for export goods is still lacking.

Investment Climate: The uncertain trajectory of global carbon pricing policies, including the CBAM, may impact investment decisions related to the LNG project. If highlighted and leveraged, the project’s inherently low CO2 footprint could attract investment by showcasing its commitment to sustainable energy production.

Policy Recommendations

Strategic Engagement: Tanzania should pursue active dialogue with EU policymakers to understand the evolving CBAM regulations and advocate for fair treatment of low-carbon intensity projects like Tanzania’s LNG.

Enhanced Carbon Mitigation: Leveraging its low CO2 emitting LNG, Tanzania should continue to invest in renewable energy integration and carbon capture technologies to further decrease the carbon footprint of its LNG and potentially fossil  based exports.

Market Diversification: Given the LNG market’s tilt towards Asia, Tanzania should bolster efforts to diversify its export destinations, thereby reducing dependency on any single market and mitigating risks associated with CBAM. However, it is possible that in the near future CBAM would incentive Asian EU partners to adopt a carbon price mechanism because the amount charged as part of the CBAM deduces the current carbon price applied in the country of origin and these countries may impose tax on their imports to cover for the carbon tax when producing goods for export to EU.

Policy Development: There is no one-size-fits-all approach to designing and implementing CBAM to tackle competitiveness and carbon leakage; policy design and characteristics of the economy matter(Zhong & Pei, 2024).Tanzania should continue to develop and refine its carbon policy and trading regulations to align with international standards and practices, thereby enhancing the attractiveness of its export products including LNG in a carbon-conscious global market. This includes technical support for carbon accounting and regulatory compliance.

Conclusion:

The broader implications for energy exports and the evolving scope of CBAM necessitate proactive measures from Tanzania. While the CBAM presents challenges, it also offers Tanzania an opportunity to position its LNG project as a leader in low-carbon energy production. By engaging proactively with international partners, investing in carbon mitigation, and diversifying markets, Tanzania can enhance the resilience and competitiveness of its LNG exports in the face of evolving global carbon pricing mechanisms.


References

Magacho, G., Espagne, E., & Godin, A. (2024). Impacts of the CBAM on EU trade partners: Consequences for developing countries. Climate Policy, 24(2), 243–259. https://doi.org/10.1080/14693062.2023.2200758

Perdana, S., Vielle, M., & Oliveira, T. D. (2024). The EU carbon border adjustment mechanism: Implications on Brazilian energy intensive industries. Climate Policy, 24(2), 260–273. https://doi.org/10.1080/14693062.2023.2277405

Sabyrbekov, R., & Overland, I. (2024). Small and large friends of the EU’s carbon border adjustment mechanism: Which non-EU countries are likely to support it? Energy Strategy Reviews, 51, 101303. https://doi.org/10.1016/j.esr.2024.101303

Zhong, J., & Pei, J. (2024). Carbon border adjustment mechanism: A systematic literature review of the latest developments. Climate Policy, 24(2), 228–242. https://doi.org/10.1080/14693062.2023.2190074

[1] https://www.riotimesonline.com/tanzania-lng-project-42-billion-host-agreement-2026/

[2] https://tracker.carbongap.org/policy/carbon-border-adjustment-mechanism/

[3] Let Me Ship, https://www.letmeship.com/en/the-eu-carbon-border-adjustment-mechanism/

[4] ibid

How Tanzania Government can Repurpose Youth for SDGs, NDCs and for a fossil free future


Photo Credit: Youth Global Climate Summit 2023

Author: Arafat Bakir Lesheve, Junior Associate, Governance and Economic Policy Centre and SDG Ambassador

Abstract

This short study and policy brief exposes the gaps and the need to repurpose the contribution of the youth in achieving the NDC and SDGs in Tanzania. The brief concludes that with tweaks to its current climate change governance framework and practice landscape, by purposefully targeting involvement of more young people, Tanzania’s achievement of its SDGs and NDC targets for climate resilience and a fossil free future can be achieved faster

Introduction
Young people are the majority of Tanzania’s population and destined to inherit the future yet are seriously at a risk of climate change. Many young people are actively engaged in mitigation measures such as tree planting campaigns with limited focus on the policy and practical measures that are required to ensure or determine a fossil free future is achieved.  In 2021 Tanzania developed its Nationally Determined Contributions (NDCs), which spells on how the government plans to build resilience against climate change and contribute to clean future. The NDC is anchored on delivering a fossil free future by 2050 yet the document and its implementation has remained largely a technical exercise with limited knowledge and participation of young people.

This short brief exposes the gaps and the need for an intentional repurposing of Tanzania’s youth in climate change and the implementation of the NDC along with the Sustainable Development Goals (SDGs) so as to achieve a fossil free future by 2030 and 2050. 

Background

The transition to a fossil-free future is crucial for Tanzania to achieve sustainable development and combat climate change. The United Nations has set several targets for achieving a fossil-free future by 2030 and 2050. These targets aim to enhance international cooperation in the fight against climate change, promote clean energy research and technology, reduce reliance on fossil fuels, reduce greenhouse gas emissions and speed up the transition to clean and renewable sources of energy.

Young people are the majority of Tanzania’s population and destined to inherit the future yet are seriously at a risk of climate change.

In 2021 Tanzania developed its Nationally Determined Contributions (NDCs), which spells out how the government plans to build resilience against climate change and contribute to clean future. The NDC is anchored on delivering a fossil free future by 2050 yet the document and its implementation has remained largely a technical exercise with limited knowledge and participation of young people. Many young people are actively engaged in mitigation measures such as tree planting campaigns with limited knowledge, focus, engagement and participation in the policy and practical measures that are required to ensure or determine a fossil free future is achieved.  With the youth comprising over 65% of Tanzania’s total population, engaging and empowering young people will be crucial to the success of these national and global targets.

Climate Change and a Fossil Free Future in Tanzania

Despite being among the least polluters, Tanzania is seriously affected by climate change. The country has experienced irregular rainfall patterns, extended droughts, floods and deforestation. Currently, a significant proportion (about 70%) of all types of natural disasters in Tanzania are climate change related and are linked to recurrent droughts and floods.

The most recent projections for climate change in Tanzania (Future Climate for Africa, 2017)9 show a strong agreement on continued future warming in the range of 0.8°C to 1.8°C by the 2040s, evenly distributed across Tanzania. The warming trend leads to a corresponding increase in the number of days above 30°C by 20-50 days in the central and eastern parts and up to 80 additional days in the coastal area of Tanzania.  Warming until 2090 is projected in the range of 1.6°C to 5.0°C depending on the level of greenhouse gases in the atmosphere( (URT: Tanzania Nationally Determined Contribution, 2021)

The extreme weather patterns affect National Economic growth due to large dependence of Tanzania’s Growth Domestic Product (GDP) on Climate sensitive activities such as agriculture. The recent floods affected crops and farmland while the extended droughts in some regions have increased food insecurity and poverty by almost half.

Moreover, climate change’s impact on Tanzania’s forest cover and sensitive ecosystems has been increasing.  According to reports, Tanzania’s forest cover has reduced by at least one third over the past decade, thereby reducing the coverage of the natural carbon sink that has protected us for generations.  Annually, almost 38% of Tanzania’s forest cover is being lost at the rate of about 400,000 ha annually and should this continue, the country would deplete its forest cover in the next 50-80 years[2]

Figure 1: Map of forest loss in Tanzania during 2010–2017 and location of ground survey points

Sensitive ecological and biodiversity systems hosted within from forests and wooded areas are affected and climate related diseases such as malaria in previously cold and less malaria prone regions such as Moshi, Arusha, Lushoto, Iringa and Mbeya are on the increase.

 According to medical reports, malaria is a major public health problem in mainland Tanzania and a leading cause of morbidity and mortality, particularly in children under five years of age and pregnant women.  Moreover, the climate condition has become favourable for transmission throughout almost the entire country, with about 95% of mainland Tanzania at risk. Over the past few years Tanzania now has the third largest population at risk of stable malaria in Africa after Nigeria and Democratic Republic of the Congo[3]. Clearly, there is a nexus between climate change and the social-economic and public policy challenges that Tanzania faces.

The perilous search for a Fossil Free Future

The UN under the Agenda 2030 targets to achieve a fossil free future by reducing global greenhouse gas emissions by half by 2030 and to achieve net zero by 2050.

For this to be feasible the world has to gradually transit from the use of fossil-based fuels towards renewables and clean energy sources.  Fossil fuels, such as coal, oil and gas, are by far the largest contributor to global climate change, accounting for over 75 percent of global greenhouse gas emissions and nearly 90 percent of all carbon dioxide emissions.

Therefore, ramping up investment in alternative sources of energy that are clean, accessible, affordable, sustainable, and reliable offers a way out of the enormous climate change challenges that we face. To achieve this requires a radical shift in global energy system but equally collective participation.  The UN has encouraged countries to develop and implement Sustainable Development Goals (SDGs) and Nationally Determined Contributions (NDCs), as road maps towards a sustainable cleaner future, yet many countries like Tanzania face a bumpy road ahead. The underfunding and limited meaningful participation by the youth is holding back success.

Climate Change, SDGs and the Nationally Determined Contributions (NDC) in Tanzania

In line with the UN Paris Agreement and call to climate action, the Tanzanian government set targets for climate change response and achieving a fossil-free future. The government aims to accelerate mitigation and adaptation measures, cutting Green House Emissions and contributing towards a transition to cleaner and renewable sources of energy.

These targets are clearly stipulated in Tanzania’s National Adaptation Plans (NAPs), National Climate Change Response Strategies (NCCRS) and most recently the Nationally Determined Contributions (NDC) in 2021.  The NDC provides a set of interventions on adaptation and mitigation which are expected to build Tanzania’s resilience to the impacts of climate change and at the same time contribute to the global efforts to reduce greenhouse gases.

According to the NDC, the government commits to reduce greenhouse gas emissions economy-wide between 30- 35% relative to the Business-As-Usual (BAU) scenario by 2030. The NDC further indicates that about 138-153 million tons of Carbon dioxide equivalent (MtCO2e)-gross emissions is expected to be reduced depending on the baseline efficiency improvements, consistent with its sustainable development agenda.  

The NDC goals are aligned to the UN Sustainable Development Goals (SDCs) 2015, in particular SDG13 and other closely related goals such as SDG (1.7,12,14,15.16 &17). They further in synchrony with the Agenda 2063 on the Future of Africa We want and the Sendai Framework on Disaster Risk Reduction (2011).

To achieve these targets, the government commits to consider the impacts of climate change in development planning at all levels and to pursue adaptation measures as outlined in the NDC. Despite these efforts, many SDG targets are off course and NDC’s implementation has been slow. The NDC implementation is faced with financial, governance, institutional and participation gaps, which are delaying or may ultimately thwart its successful achievement of a climate safe and fossil free future.

Gaps in Climate Change, NDC and SDG implementation

The Economics of climate change and implementation of SDGs and the NDC for a climate safe and fossil free future is proving to be an expensive affair.

According to The Economics of Climate Change reports for Mainland Tanzania (2011) and Zanzibar (2011) , an initial cost estimate of addressing current climate change risks is about USD 500 million per year[4].  These reports provide indicative costs for enhancing adaptive capacity and long-term resilience in Tanzania.  This cost is projected to increase rapidly in the future, with an estimate of up to USD 1 billion per year by 2030[5].

Further, the net economic costs of addressing climate change impacts are estimated to be equivalent to 1 to 2% of GDP per year by 20305. Similarly, Tanzania would require an investment of approximately USD 160 billion for mitigation activities aimed at achieving 100% renewable energy for electricity, buildings, and industry by 2050[6]. In total the NDC estimates that USD19,232,170,000 is required for its full implementation.

Moreover, Tanzania is facing several challenges related to weak institutional, financial constraints, poor access to appropriate technologies; weak climate knowledge management, inadequate participation of key stakeholders, and low public awareness have significantly affected effective implementation of various strategies, programmes, and plans[7]

The government has identified an institutional and governance framework for implementation. This includes the National Steering Committees and National Technical Committees for Mainland Tanzania and Zanzibar.  It further mentions the need for mainstreaming intervention but conspicuously, misses listing or identifying the youth as key stakeholders in this implementation.

With tweaks to its current policy and practice landscape, by purposefully targeting involvement of more young people, we believe, Tanzania’s achievement of its SDGs targets and climate change and energy transition goals as elaborated in the NDCs and overall National Development Plans could be faster.

Tanzania’s Road towards a Fossil Free Future

Tanzania’s road towards a fossil free future has so far been bumpy and marked with commitments and challenges. Tanzania however has opportunities and can turn up the ride faster.

The per capita emissions of the United Republic of Tanzania were estimated at 0.22 tCO2e[8] in 2014, which is significantly below global average of 7.58 tCO2e[9] recorded in the same year. However, given the disproportional effect of climate change, adaptation to the adverse impacts continues to be a topmost priority in the implementation of the NDC

Tanzania underlines the importance of harnessing opportunities and benefits available in mitigating climate change through pursuing a sustainable, low-carbon development pathway in the context of sustainable development. Thus, the NDC takes into account global ambition of keeping temperature increase well below 2°C as per the Paris Agreement.

Moreover, Tanzania is aiming for a greater use of natural gas and harnessing renewable energy sources to reduce on emissions. There are an estimated 57 trillion cubic feet of discovered reserves of which to-date over 100 million cubic feet have been exploited to produce 527 MW10. The government acknowledges that whilst natural gas is a fossil fuel, and therefore contributes to increasing climate change, it results in half the CO2 emissions as charcoal

Currently the government of Tanzania aims to shift away from biomass and increase the share of renewable energy sources such as hydro, wind, and solar in its energy use mix. Tanzania’s energy sector is currently dominated by traditional biomass; accounting for more than 82% of the total energy consumption as of 2019. As of 2022 energy usage in households, charcoal and wood represented 87% of the energy used, Liquefied Petroleum Gas (LPG) accounted for 10%, and other sources such as electricity accounted for about 3%[10].

Secondly, Tanzania has an estimated hydro potential of up to 4.7GW. However, as of 2021, only 573.7 MW (around 12%) of hydro capacity had been installed. The government plans to further develop its hydro capacity to increase the share of renewable energy.

Thirdly, while Tanzania aims to increase its renewable energy generation, there are also plans to ramp up investment in natural gas and coal. The government aims to reach 6700MW (33%) from natural gas and 5300MW (26%) from coal by 2044. However, further investments or reliance on fossil fuels such as coal and natural gas is considered as an energy transition risk as the country may lock itself into a high carbon-intensive pathway and thereby running contrary to achieving the NDC goals.

Furthermore, Tanzania has significant deposits of critical minerals that are considered essential for the clean energy transition. These minerals include nickel, graphite, copper, lithium, and others. The demand for these minerals expected to increase as clean energy technologies develop. This presents an opportunity for Tanzania to benefit from their extraction to value addition hence powering the global transition to a green economy.

Repurposing the youth dividend for climate change, NDCs and SDGs in Tanzania

Globally, the youth represent a significant portion of the population and their active involvement and engagement in supporting government and UN targets are essential.  

According to Tanzania’s 2022 census reports, the youth (under 35 years) constitute significant proportion (over 60%) of Tanzania’s population.  They account for the largest active labour force of the population and no doubt have potentials   to bring about economic growth and development of the country. Moreover, the demographics and dynamics of youth have changed substantially over the last decade. Many young people are highly educated and technologically exposed and skilled.  They are a dividend waiting to be utilized in many respects.

The implementation of Tanzania’s NDC is supposed to be guided by the principles of the UNFCCC, particularly the principle of equity and that of common but differentiated responsibilities and respective capabilities. Furthermore, the implementation is supposed to be implemented in a transparent and participatory manner in accordance with the provisions of the Paris Agreement. Despite these principles, the youth are yet to be fully engaged and harnessed for climate change and a fossil free future.

How can Youth be mobilized for a fossil free future?

Since 2006 government has made efforts by developing the National Climate Adaptations Programs and the National Climate Change Strategy. However, Tanzania does not have a climate change policy and its practical engagement of youth despite the numbers has been quite fragmented

Despite the major progress made, very limited deliberate and structured youth engagement opportunities have been created. For example, there is a government initiative on clean cooking targeting women but is not clear what role the youth can play in this campaign. Moreover, the Youth Policy is not aligned with the Climate Change and Energy policy. The NDC for example is very silent on Youth and mentions these in generic terms lobed together under the gender considerations. Governance challenges and weak intra-government coordination exists. There is weak insufficient capacity and resources for youth to engage.

To date, this potential of Tanzania’s youth participation, in the context of the global climate change is largely limited or focused on climate mitigation while engagement in energy transition discourse towards a fossil free future has been substantively low.

Re-prioritising Youth Engagement for Climate Change, SDGs and NDCs implementation

There are collective actions that Tanzanian youth can uptake to support government plans and UN targets for a clean future by 2030 and 2050. These includes actions such as investment in advocacy, awareness creation, skills development, creating of innovations, movement mobilization, partnership and collaboration for the goals. Tanzanian youth possess the energy, innovation, and sense of urgency required to drive the transition to a fossil-free future. By leveraging their skills and passion, young people can play a vital role with multiple entry points as below.

Raise Awareness and Advocate for Renewable Energy

As the population continues to grow, so will the demand for cheap energy, and an economy reliant on fossil fuels is creating drastic changes to our climate; Investing in solar, wind and thermal power, improving energy productivity, and ensuring energy for all is vital if we are to achieve SDG 7 by 2030.

Towards achieving this, the youth and other stakeholders, including the government should organize awareness campaigns and workshops to educate youth about the benefits of renewable energy and the negative impacts of fossil fuels. Engage in advocacy efforts to promote renewable energy policies and initiatives at the local, national, and international levels; Tanzania Youth led organizations must be supported to amplify the voices of Tanzanian youth in advocating for a transition to renewable energy.

Promote Energy Efficiency and Conservation

Tanzanian youth can organize campaigns and workshops to raise awareness about the importance of energy efficiency and conservation. They can educate their peers and communities about the benefits of using energy-efficient appliances, reducing energy consumption, and adopting sustainable practices.

Dr. Samia Suluhu Hasan the President of the United Republic of Tanzania is a global champion of clean cooking solutions that aims to address over reliance on toxic biomass, gender inequality against women as well as reduce impact of climate change.  Tanzania’s youth should be in frontline to promote clean cooking solution with the country.

In Tanzania, there are several initiatives aimed at promoting energy efficiency and conservation among youth. The United Nations Development Programme (UNDP) is actively involved in fortifying the capacity of governmental bodies, businesses, and civil society organizations to implement effective energy efficiency measures. Additionally, UNDP has launched a ground breaking scholarship program in partnership with the Ministry of Energy and the Dar es Salaam Institute of Technology, focusing on educating young women in the energy sector and honing their skills in Energy Management and Energy Audits.

These efforts not only empower women and youth but also foster collaboration across diverse segments of the population. Furthermore, The Prime Minister’s Office – Labour, Youth, Employment, and Persons with Disabilities is championing policy reforms in employment through public-private cooperation, with a focus on equal opportunity, fair pay, and gender-sensitive vocational training. These initiatives aim to empower Tanzanian youth, promote energy efficiency, and create a sustainable and inclusive future.

In SDG 5 (Gender Equality and Empowering Women), the use of biomass has resulted in social economic inequality that mainly affect women. They are unable to participate in various economic and developmental opportunities because they spent half of their time to fetch cooking charcoal. Clean cooking solution will improve their lifestyle, empower women and enable them to participate in developmental opportunities. 

For the government to support youth roles is key to encourage energy-efficient practices among youth by promoting energy-saving habits in households, schools, and communities. Youth and youth led organizations should be supported to advocate for the implementation of energy-efficient infrastructure and appliances in public spaces and buildings.

NGOs, and government agencies must collaborate with energy experts to develop engaging and interactive training materials that cater for the needs and interests of young people towards promoting energy efficiency.

Advocating for policy changes

Advocating for policy changes is a crucial step in promoting renewable energy and climate action. Tanzanian youth have the opportunity to actively engage with local and national government representatives to push for policies that support renewable energy and discourage the use of fossil fuels.

Through outreach to their government representatives, youth can express their concerns about climate change and the need for renewable energy policies. They can request meetings or participate in public forums to discuss the importance of transitioning to renewable energy sources and highlight the benefits it can bring to the environment and the economy. By sharing their knowledge and experiences, youth can help policymakers understand the urgency of taking action on climate change and recognize the potential of renewable energy.

Additionally, youth-led organizations and initiatives focused on climate action must provide a platform for young people to come together and advocate for sustainable policies. By joining these organizations, Tanzanian youth can amplify their voices and collaborate with like-minded individuals to lobby for renewable energy policies. These organizations often organize campaigns, protests, and awareness-raising events to educate the public about the importance of renewable energy and the need for policy changes. Lastly, Tanzanian youth can actively participate in lobbying efforts to influence policymakers and decision-makers. They can organize meetings with government officials, write letters, and utilize social media platforms to raise awareness about the benefits of renewable energy and the negative impacts of fossil fuels.

Moreover, youth can effectively advocate for sustainable policies that prioritize renewable energy and climate action. presenting well-researched arguments and evidence-based solutions. Through engagement with government representatives, involvement in youth-led organizations, and active lobbying for sustainable policies, Tanzanian youth can thereby make a significant impact in promoting renewable energy and driving climate action in their country.

Engage in Sustainable Agriculture and Land Use

Tanzania youth must be supported to engage in sustainable agriculture and land use. Engaging in sustainable agriculture is of paramount importance in promoting environmental conservation and reducing reliance on fossil fuel-based inputs in farming practices. Tanzanian youth have a significant role to play in actively supporting and advocating for sustainable farming methods that prioritize organic techniques, agroforestry, and permaculture. By reducing the dependence on chemical fertilizers and pesticides, young individuals can make valuable contributions to preserving biodiversity and curbing greenhouse gas emissions.

The promotion of organic farming methods not only fosters healthier and more sustainable food production but also safeguards soil health and water quality. Furthermore, agroforestry practices, such as the integration of trees into agricultural landscapes, can bolster biodiversity, enhance soil fertility, and create additional income streams for farmers.

Embracing permaculture principles, which revolve around designing sustainable and self-sufficient agricultural systems, can further bolster the resilience and long-term sustainability of farming practices. By embracing sustainable agriculture, Tanzanian youth can play a pivotal role in constructing an environmentally friendly and resilient food system.

Foster Entrepreneurship and Innovation in Renewable Energy

Support young people to engage in entrepreneurship and renewable energy. Participating in green entrepreneurship presents Tanzanian youth with exciting prospects to contribute to the sustainable energy sector while establishing their own businesses. By developing innovative solutions for energy efficiency and conservation, young entrepreneurs can make a positive impact on the environment and contribute to the country’s economic growth. There are several avenues for Tanzanian youth to explore in the green economy, including manufacturing energy-efficient products, providing energy auditing services, specializing in renewable energy installation and maintenance, offering energy consulting and training, and developing waste-to-energy solutions. Through these endeavours, young entrepreneurs can both drive environmental sustainability and create economic opportunities for themselves and their communities.

Engaging in waste management practices

Promoting environmental sustainability and mitigating the harmful effects of waste necessitate active engagement in waste management practices. Tanzanian youth can play a vital role by championing recycling, composting, and waste reduction initiatives within schools, communities, and households. By raising awareness about recycling’s significance and providing resources for proper waste separation, the youth can redirect recyclable materials away from landfills, thus fostering a circular economy. Moreover, they can advocate for composting as an effective means of minimizing organic waste while generating nutrient-rich soil for gardening and agriculture.

Participating in clean-up campaigns and initiatives represents another impactful avenue for youth to drive awareness about the environmental repercussions of waste. By organizing and actively participating in clean-up activities in public spaces, beaches, and natural areas, they can underscore the importance of responsible waste disposal and inspire others to take similar action. Through their enthusiastic involvement in waste management, Tanzanian youth can contribute significantly to creating cleaner and more sustainable communities and a brighter future for the environment.

References

Critical Minerals and Energy Transition in Tanzania: A new dance, maybe? Policy Forum (2022); https://www.policyforum-tz.org/blog/2022-06-14/critical-minerals-and-energy-transition-tanzania-new-dance-maybe

Fossil Fuels Cast Dark Shadow Over Tanzania’s Green Future – Health Policy Watch; (https://healthpolicy-watch.news/fossil-fuels-cast-dark-shadow-over-tanzanias-green-future/)

URT; Nationally Determined Contributions ; 1.5°C national pathway explorer – Tanzania (NDC); https://1p5ndc pathways.climateanalytics.org/countries/tanzania/current-situation/

Governments plan to produce double the fossil fuels in 2030 than the 1.5°C warming limit allows

Net Zero by 2050 – Analysis – IEA

Renewable energy – powering a safer future | United Nations

Sustainability | Free Full-Text | A Global Assessment: Can Renewable Energy Replace Fossil Fuels by 2050?

United Nations Development Programme

United Nations Development Programme. (2022). Elevating Meaningful Youth Engagement for Climate Action. Retrieved from link United Republic of Tanzania .:. Sustainable Development Knowledge Platform

[1] URT: Tanzania Nationally Determined Contribution, 2021

[2] https://dicf.unepgrid.ch/united-republic-tanzania/forest

[3] https://web-archive.lshtm.ac.uk/www.linkmalaria.org/country-profiles/tanzania.html

[4] The Economics of Climate change in the United Republic of Tanzania, January 2011

[5] Ibid

[6] URT; Tanzania’s Nationally Determined Contributions, 2021

[7] URT; Tanzania’s Nationally Determined Contributions, 2021

[8] National Climate Change Strategy, Vice President’s Office, United Republic of Tanzania.

[9] Emissions Database for Global Atmospheric Research (EDGAR), Joint Research Centre (JRC).

[10] ibid

Social Economic Impact of Climate Change on Indigenous Communities: A case of Hadzabe Indigenous people of Tanzania

A lot of climate change coverage and advocacy in defense of indigenous communities is largely focused on other parts of the world such as the Amazonian and Andean communities yet little attention is given to African indigenous communities. Without immediate action, we warn, the Hadzabe livelihoods and communities could gradually be wiped into extinction.

Author: Eva Kihupi, Junior Associate, Governance and Economic Policy Center

(Featured photos sourced from: Africa 101 Last Tribes online website-https://www.101lasttribes.com/tribes/hadzabe.html)

1.0 Introduction to Climate Change and Indigenous Communities

Africa has a lot of indigenous groups critically exposed to the dangers of climate change with little support. These constitute the left behind in climate governance and the quest for climate Justice. This short analytical study and brief highlights the relevance of taking action to mitigate the problems created by climate change on African indigenous communities, with a focus case on the Hadzabe indigenous communities of Tanzania.  

Amidst a world transformed by climate’s embrace, Indigenous communities bear the deepest scars. Their ancestral lands, rich in spirit, face unprecedented challenges. In their resilience lies a profound wisdom, urging us to unite for a future where all thrive in harmony. 

Current studies show a positive correlative evidence of climate change’s impacts on increased temperatures and declining biodiversity in sensitive nature ecosystems. This makes indigenous groups the first group to be directly affected and more disadvantaged by the negative impacts of climate change due to their direct reliance on the natural environment. Moreover, the impacts of climate change are more severe, long lasting, socially disruptive on indigenous communities than other population groupings.

According to the United Nations “Indigenous communities, peoples and nations are those which, having a historical continuity with pre-invasion and pre-colonial societies that developed on their territories, consider themselves distinct from other sectors of the societies now prevailing on those territories, or parts of them.

Indigenous people are therefore distinct social and cultural groups that share collective ancestral ties to the lands and natural resources where they live and occupy.  By nature, the indigenous people are heavily reliant on their natural environment and local ecosystems for livelihoods and survival.

The UN further estimates that the total net impact of climate change on indigenous communities is in billions of dollars and intergenerational. Despite being the least polluters, the indigenous communities are paying heavily for the climate change crimes and damages that they never caused. Their lands, dwellings, livelihoods and cultures are being disrupted and wiped out. Their future generations may never exist or even live to enjoy their cultural heritage.

While the impacts of climate change on indigenous communities are almost similar, a lot of global climate change coverage and advocacy in defense of indigenous communities is largely focused on other parts of the world such as the Amazonian, Andean and pacific communities.

Little attention is given to African indigenous communities. Yet Africa has a lot of indigenous groups critically exposed to the dangers of climate change with little support. In our assessment, these constitute the left behind in climate governance and the quest for climate Justice.

2.0 Why Indigenous Communities Matter in Climate Change Justice

Indigenous peoples comprise less than five percent of the global population but protect more than 80 percent of its biodiversity. Indigenous people play a great importance in climate solutions alongside their need to have access to resources[1].

When the rights of Indigenous peoples are recognized, secured, and protected, rates of deforestation tend to be lower and carbon stocks tend to be higher than in forests managed by other actors. Secure rights for community forest guardians can also improve ecosystem integrity, protect biodiversity, and enhance public health

Climate change exacerbates the difficulties already faced by indigenous communities.  This includes social and economic marginalization, loss of ancestral land for hunting, gathering and water resources for livelihood. Encroachment from external actors aggravating, human rights violations and discrimination based on cultural differences. 

By addressing the critically climate change problems and concerns facing indigenous communities equally, governments and the world can strike a double win of achieving long lasting solutions to climate change and at the same time contributing to securing the unique cultural diversity and livelihoods of indigenous communities for future generations.

3.0 Climate Change and the Hadzabe People of Tanzania

Hadzabe Homeland Map: Source- Africa 101 Last Tribes

The Hadzabe people reside in a 4000 km2 area around the shores of Lake Eyasi in Northern Tanzania, East Africa. The total small population size of approximately 1000 to 2,000 individuals, has shown no major disruption during the past 100 years. According to the 2015 National Census report the Hadzabes range between 1,200 to 1,500 but this number has been dropping.

Only around 150 to 200 individuals of these, however, currently practice a predominantly hunting and gathering way of life, meaning that the bulk of their diet is derived from wild plant foods and game animals.  Because of climate change related factors, many have been either displaced or forced to abandon their ancestral lands and culture and escaped to urban centers in search for better livelihoods.

The Hadzabe are more prone to the impacts of climate change than any other community because they are very highly dependent on the environment and climate compared to other social groupings in Tanzania.

Over the years, the Hadzabe’s have been facing the vagaries of climate change head-on and yet very little efforts are made to highlight their plight and address the climate change risks that they face.  The risks are socio-economic, health and cultural in nature yet have serious human rights and justice violations connotations that are silently overlooked.

Their livelihood is entwined with the climatic environment where they live, and therefore it is important to have appropriate means to tackle the impacts of climate change and its adverse effects on these indigenous people. 

 Environmental degradation and livelihoods

Firstly, the rising temperatures and extended droughts have resulted in a loss of vegetation and negatively impacted gathering and hunting activities undertaken by the Hadzabe people. Their hunting and eating habits have changed as they now have to turn to unconventional hunting methods and eating of endangered animal such as monkeys, baboons and rare bird species to compensate for the dwindling plant and animal species that previously provided food.  Increasingly the Hadzabe are gradually becoming a danger to the animals and an ecosystem that they protected for many generations earlier.
 Health and morbidity risks

Moreover, the health of the Hadzabe indigenous people is deteriorating as they no longer get their livelihood from nature.  The Hadzabe’s are very well known to feed on meat from wild game, honey, and plants, including tubers, berries, and baobab fruit[1].  For the Hadzabe, the phrase “food is medicine” is applicable and yet the increased climate impacts like heat waves, storms and flash floods have wiped out their food sustenance. Because of climate change, the flower bearing trees are rare and the bees are dying or migrating to distant places in search for green forest cover.

The already inadequate access to health facilities such as hospitals amidst declining immunity has caused more danger for the indigenous people who live in the wilderness and have to roam deeper in search for food.  According to medical reports from the nearest medical facilities such as the Haydom Lutheran Hospital, the morbidity and mortality rates amongst this small Hadzabe community in Yaedachin Valley has increased.

The level of alcoholism and substance abuse has increased as they look for alternative ways to survive the harsh living conditions in a changing natural environment. The leading causes of death are malaria, respiratory diseases, anemia and cardio-circulatory disease and maternal mortality rates amongst the women and children.[2]

Limited supportive infrastructure, social services and opportunity

Furthermore, lack of supportive social infrastructure such as clean water sources have increased vulnerability to the negative impacts of climate change. The water streams have dried up and the few surviving are shared with wild animals, increasing the risks of contamination and disease.  Women and children have to walk long distances in search of water and this has disrupted their traditional family settings, learning and increased to exposure to gender-based violence.

 Enhanced climate induced emergencies affecting for Hadzabe

Figure 2: Percentage of Natural Resource disasters from 1980-2022 in Northern part of Tanzania

The increased droughts and erratic rainfalls have increased vulnerability and occurrence of natural climate driven disasters such as flush floods affecting the Yaedachini Valley where the Hadzabe live. According to the Tanzania Prevalence of Natural Disasters Report (1980-2022), Northern Tanzania now suffers from recurrent floods and droughts, and the frequency (and severity) of events has been increasing. 

The adjacent pie chart shows the percent share by type of natural disasters recorded in Northern Tanzania between 1980-2022. According to this statistics floods and drought account for more than 71% of the total disasters recorded. This proves that the impacts of climate change are affecting the drier part of Northern Tanzania, where the Hadzabe live more than any other parts of the Country.

The Hadzabes live in Yaedachini Valley on the floors of the Eastern Rift Valley Escarpments located in Babati, Hanang, Haydom, Mbulu districts corridor of Manyara region which have become more susceptible to drought and flash floods.

The recent examples of enhanced climate induced emergencies were the flash floods and mudslides which affected Babati and Mbulu district in 2023 killing hundreds and living thousands homeless[1].  During these last flash storms and floods, it is estimated that at least 60% of the Hadzabe dwelling places in the Yaeda valley were affected and many left without food and shelter.   The consequences to their livelihoods were more severe as they are directly more reliant on the natural environment than any of their neighboring social groupings. Yet very little national and global coverage and attention was provided.

The Natural disasters reports from Tanzania’s Prime Minister’s Office confirms, the severity of climate change related disasters such as floods has been increasing in the country. For example, the heavy rains and floods  that occurred in Tanzania between 28th March and 28th April 2024   claimed around 155 lives. This was so far the highest number of flood related deaths ever recorded in the country[2].  The damages were more severe in drought prone regions such as Manyara region. If not addressed therefore, the Hadzabes and other indigenous groups in these disaster-prone areas could be wiped out.

 Climate Injustice implications to the Hadzabe

Further, climate change has significant human rights and justice implications on indigenous groups. The indigenous Hadzabe people are facing numerous injustices and violations of their socio, economic and cultural rights due to climate change. Their socio-economic rights are not guaranteed, and their indigenous lands are not protected, putting them at risk of extinction.  They are also facing threats to their right to food, shelter, and ancestral lands, as they may be forced to leave their traditional lands in search of alternative livelihoods.

Climate induced migration and cultural injustices

The Hadzabe’s culture is being adulterated by new communities such as the cattle keeping and farming Datoga tribes who are moving into Hadzabe lands in search for pasture and new settlement. The numbers of new comers are increasing while their Hadzabe numbers are dwindling, making them increasingly a minority and vulnerable[1]. Their location in hard-to-reach areas and lack of access to education and formal skills has increased their economic marginalization as an indigenous group and limits their opportunities to employment and a better future. 

In the midst of all these, there are critical policy and governance actions that must take and the international community must support to bring the Hadzabe from the behind to the front. From near extinction to future survival.

4.0 Recommendations for action

  1. Tanzania government must recognise Hadzabe as an indigenous group for protection by both national and international mechanisms against climate change and extinction. Despite voting in favor of the UN Declaration of the Rights to Indigenous peoples, Tanzania does not recognize the existence of any indigenous peoples in the country and there is no specific national policy or legislation on indigenous peoples per se. The absence of such makes protection of the Hadzabe with in the ambits of national and international frameworks weak. On the contrary, a number of policies, strategies and programs that are misaligned to the interests of the indigenous peoples in terms of access to land and natural resources, basic social services and justice are continuously being developed, resulting in a deteriorating and increasingly hostile environment for both pastoralists and hunter gatherers[2].   In a recent move in 2022 and 2023, the government relocated hundreds of Masai and Hadzabe families from the Loliondo Ngorongoro area to Tanga, hundreds of kilometers away from the ancestral land[3]. This was to pave way for expansion of private game hunting grounds of a Dubai based firm.  This move was widely condemned by Human and Land rights defense organizations, as reflective of the risks that indigenous groups face in Tanzania. Despite global condemnations, the government did not change its decision.
  1. Tanzania government must establish a dedicated fund towards climate change mitigation and adaptation measures targeting the Hadzabe. The Tanzanian Government and parliament must allocate a special vote in its national budget to cater for climate change mitigation, adaptation and protection of indigenous communities at frontline of climate change. While the government funds climate change and disaster related activities through line Ministries, Departments and Agencies such as the Prime Minister’s Office, the Vice President’s Office- Environment, Ministry of Tourism and Natural resources etc., it is evident that such funding lines can be conflated and blurred due to over competing priorities. The net consequences have been that less dedicated funding is reaching the extremely vulnerable and left behind in climate change such as the Hadzabe who desperately need it for survival. Tanzania is yet to establish a fully-fledged National Climate Fund and the current climate change related funding has been largely foreign sourced and quite unsustainable[4]
  1. The UN and other international agencies must dedicate percentage of the Loss and Damage Fund to cater for indigenous groups including the Hadzabe in Tanzania. During the COP27 in Egypt, the United Nations committed to setting up a climate loss and damage fund. While as the details of this Fund are still unclear, the framework for access of these funds is still being developed. This provides an opportunity for putting guard rails as to how indigenous groups such as the Hadzabe will benefit. Reports from climate champions indicate that a very small fraction of funding is currently directed towards Indigenous Peoples and Local Communities (IPLC) for securing land rights and managing forests in tropical regions. Over the past decade, a minimal portion of the resources designated to support IPLC’s land rights and forest management actually involved an IPLC organization. This accounts for an insignificant share of the overall climate change assistance. Additionally, from the financial commitments made during the COP26 IPLC Forest Tenure Pledge for the period between 2021 and 2025, only a minor percentage of those funds has been utilized[5].
  1. Tanzania government must provide adequate infrastructure and social services like health, water services, and education for future sustainability. The Tanzanian government in collaboration with other state actors or non-state actors such as CSO, community-based organization must provide supportive social-economic infrastructure[6] such as wells, boreholes, and water tanks to the Hadzabe communities. This will help provide the Hadzabe with access to clean and reliable sources of water and opportunities for learning and acquiring new skills to confront climate change. Alternative means of food must be equally provided to complement the dwindling wild sources.  
  1. Scale up indigenous conservation and tame nugatory land grabbing of indigenous lands. The government ministries and departments responsible for environment, conservation and lands must address the persistent land grabbing and encroachment on ecosystems that support indigenous groups such as the Hadzabe. Since the indigenous people heavily rely on the natural environment to sustain themselves it must be a priority to preserve and even promote indigenous conservation of their natural environment. Proclaiming more places as conversation areas and restricting deforestation or intrusion and allowing access for the indigenous communities to live and enjoy the natural habitats, such as Yaeda Chini valley will be a game changer in ensuring continued existence of the Hadzabe[7].
  1. Create space at the table for the Hadzabe, to directly speak and advocate for their interests at both national and international levels. Creating forums and opportunities for the Hadzabe to sit at the table as active participants in national climate change dialogues spaces would help raise awareness of the magnitude of their plight at national level. Having the Hadzabe constitute part of the National Delegations to international forums like the forthcoming COPs, is essential in highlighting their concerns at international level and creating international consensus. Direct representation in forums like parliament and the United Nations would amplify their voices and influence suitably tailor-made solutions to their needs. This will empower the Hadzabe to advocate for effective climate change mitigation policies and support based on their firsthand experiences.

 References and notes

  1. IMF (2023), ‘Building Resilience to Climate Change’. Country Report No 23/154. https://doi.org/10.5089/9798400241772.002
  2. The Water Supply and Sanitation Act, 2019 (s. 4). Available at https://tanzlii.org/akn/tz/act/2019/5/eng@2019-02-22
  3. Khatibu, F. A., Msami, J., Mchallo, I and Gontako, J (2022, June). ‘Climate Finance Availability and Access in Tanzania’ (Issue Brief No 04/2022) :https://www.repoa.or.tz
  4. https://education.nationalgeographic.org/resource/thehadzaoftanzania/
  5. 29 No. 1 (2022): ‘Tanzanian Journal of Population Studies and Development’. https://doi.org/10.56279/tjpsd.v29i1
  6. Laltaika, E. & Parmello, S. (2012). ‘International Work Group for Indigenous Affairs: Indigenous Peoples in Tanzania’. https://www.iwgia.org/en/tanzania/897-update-2011-tanzania
  7. Race to Resilience. ‘Indigenous Peoples and The Race to Secure Self-Determined Finance’: https://climatechampions.unfccc.int/system/indigenous-peoples-finance/
  8. National Geographic, (2023): ‘Evolution of Diet – The Hadza of Tanzania’. https://education.nationalgeographic.org/resource/the-hadza-of-tanzania/
  9. National Library of Medicine (2018). ‘Cause-specific mortality patterns among hospital deaths in Tanzania, 2006-2015’. https://doi.org/10.1371%2Fjournal.pone.0205833
  10. Association of Member Episcopal Conferences in Eastern Africa (2023). ‘TANZANIA: TEC Sends Humanitarian Aid and Condolences after Deadly Mudslide Hits Hanang Manyara’. https://communications.amecea.org/index.php/2023/12/08/tanzania-tec-sends-humanitarian-aid-and-condolences-after-deadly-mudslide-hits-hanang-manyara/
  11. Lasteck, A., (2024). ‘Tanzania floods and landslides kill more than 150’. BBC News 25 April https://www.bbc.com/news/world-africa-68896454
  12. Karashani, B (2022). ‘Tanzania spends millions to move, build new life in Tanga for Loliondo Maasai’ The East African. https://www.theeastafrican.co.ke/tea/news/east-africa/tanzania-relocates-loliondo-maasai-to-tanga-3860046
  13. Dave, ‘The Hadzabe of the Yaeda Valley’ A Step Ahead. https://www.astepahead.es/the-hadzabe-of-the-yaeda-valley/


[1] Tanzanian Journal of Population Studies and Development, Vol. 29 No. 1, 2022: 44-64

[2] https://www.iwgia.org/en/tanzania/897update2011tanzania  

[3] https://www.theeastafrican.co.ke/tea/news/east-africa/tanzania-relocates-loliondo-maasai-to-tanga-3860046


[4] https://www.repoa.or.tz/wp-content/uploads/2022/10/Climate-finance-availability-and-access-in-Tanzania-.pdf

[5] https://climatechampions.unfccc.int/system/indigenous-peoples-finance/

[6] Section 23 of the water supply and sanitation act, 2019 

[7] https://www.astepahead.es/thehadzabeoftheyaedavalley/  

[1]https://communications.amecea.org/index.php/2023/12/08/tanzania-tec-sends-humanitarian-aid-and-condolences-after-deadly-mudslide-hits-hanang-manyara/

[2] https://www.bbc.com/news/world-africa-68896454

[1] https://education.nationalgeographic.org/resource/the-hadza-of-tanzania/

[2] https://www.ncbi.nlm.nih.gov/pmc/articles/PMC6209209/  


[1] https://climatechampions.unfccc.int/system/indigenous-peoples-finance/


The Nexus of Climate Change and Energy Transition on women in Tanzania: Why and how government must address gaps

While Tanzania has made some progress in addressing climate change, significant policy and governance gaps to leverage women power still exist. Addressing these gaps requires putting in place a Climate Change policy, strengthening institutional capacity, enhancing coordination, improving legal frameworks, promoting transparency, and ensuring women inclusive decision-making processes backed with sustainable funding. An organ similar to a National Women in Climate Change and Energy Council, could be an ideal vehicle for channeling and championing women participation in climate change and energy transition in Tanzania. Conducting periodic women congresses on Climate Change, Gender and Energy Transition would propel this even further.

Author(s):  Gloria Shechambo, Researcher and Moses Kulaba,  Governance and Economic Policy Centre

Featured Photo: Courtesy of Pastoral Women Council, Tanzania (Africa Climate Adaptation Centre)

As covered in  the first part of this analytical brief, Tanzania has made some progress in addressing climate change by putting in place a number of frameworks. While these frameworks provide a foundation, more targeted policies integrating gender considerations are essential to promote women’s participation and leadership of climate change and energy justice driven initiatives. To date, significant governance gaps still undermine efforts to address climate change and energy concerns in Tanzania.           

 In Tanzania, the main policy and governance gap is that the Country does not have a single comprehensive Climate Change Policy to guide the governance of the sector. As a consequence there are significant coordination and risks for duplicated efforts spread across different documents and institutions, with little synergy.

Moreover issues of  women concern in climate change and energy are not tackled as an independent urgent contemporary issue but has been mainstreamed in this labyrinth of policy and regulation framework.

The problem with this mainstreaming approach is that when a critical issue such as gender is mainstreamed, it fades into depth of elaborate policy texts and loses the core urgency that it deserves. In fact, instead of getting mainstreamed, the issue gets out streamed and gradually loses core attention.

For example, while the National Climate Change Response Strategy 2023 is keen on Mainstreaming Gender, it does not provide a distinct organ through which women can channel their opinions on matters related to climate change and energy. Similarly, the National Strategy for Mainstreaming Gender in Climate Change (NSMGCC) is weak in this area. A part from providing guidance on how gender considerations should be made in policies and budgeting matters, the document does not create a distinct forum for women.  

The National Energy Policy 2015 (NEP 2015) is awkwardly silent on gender in energy sector and therefore does not provide and pivots on which a compressive engagement of women in energy can be built.  The LPG promotion plan and the National Gas Utilisation Master Plan have largely remained an implemented and the recent clean cooking gas initiative is an attempt to put this into action[1].

The government acknowledges that despite significant progress from the above efforts by the government and other stakeholders, there remain needs for increased mainstreaming of gender at all levels of climate change interventions including in policy, programs, strategies and activities using appropriate gender lens and mainstreaming instruments. Approaches such as gender analysis, gender audit and gender budgeting using gender disaggregated data in M+E and reporting on all climate change responses should be enhanced[2].

Moreover, the financing of women led and targeted climate change and just energy transition initiatives has been low and unsustainable. While the Clean Cooking Initiative in Tanzania is commendable, the downside of this is that it is largely donor funded, private sector driven and thus its long-term funding and wide scale affordability is largely unguaranteed.

Tanzania has set a target of achieving 50% renewable energy generation by 2030, however, budgetary allocations to support climate change mitigation and adaptation have generally focused on sectors like agriculture, water, and forestry, which are highly vulnerable to climate change. However, overall allocation specifically targeting climate change mitigation and adaptation remains relatively low compared to the needs identified in national strategies. According to a Research Report by REPOA, climate financing sources do not meet the expectations as by 2020 a total of TZS 24.7 trillion equivalent to USD 10.7 million were mobilized during FYDP II, which was only 3.6% of the targeted amount[3]

According to Africa Enterprise Foundation (AEF), the Tanzania Clean Cooking Project (TCCP) is a US$3.75 million three-year project, funded largely by the Government of Sweden, that aims to catalyse the clean cooking sector through enhanced private sector participation. The project will provide matching grant financing and technical assistance to small and growing businesses working in clean cooking. The financing aims to de-risk companies to venture into underserved markets and enhance the affordability and accessibility of clean cooking solutions for at least 60,000 beneficiary households.

By requiring or expecting the poor women in rural areas to switch from free firewood and biomass to paid cooking gas (LPG), the initiative places poor women directly into the market place driven energy cash economy which may be expensive and unsustainable to afford. According to the Ministry of energy, so far only 50% of rural women enrolled on to this initiative have continued[4]. For this initiative to succeed, the issues of reduced cost, increased household incomes and sustainability of supply must be addressed.

Generally, essential milestones need to be covered. These include lack of a comprehensive policy  coordination fragmentation, limited institutional capacity, inadequate or duplicative legal frameworks, weak enforcement mechanisms, and insufficient participation of women in designing, championing and leading initiatives that affect their welfare (Nachmany, 2018).

Why engaging women in Climate Change and Energy Matters:

Engaging women in climate change and energy transition decision-making processes is crucial and pays dividends. According to the UN and documented evidence in development, empowering women bears lasting solutions and can a be a multiplier factor in addressing climate change and achieving sustainable development.

Women make up nearly half of the agricultural labor force in developing countries. When provided with the same access to resources as men, women can increase their agricultural yields by 20 to 30 percent. This boost in productivity not only improves total agricultural output by 2.5 to 4 percent, but it can also help reduce world hunger by 12 to 17 percent.

Empowering women especially in rural areas in agriculture can also have a positive impact on climate adaptation. By providing appropriate technology and resources, we can promote more sustainable farming and conservation practices. And by reducing poverty, we can help individuals better adapt to the effects of climate change.

When it comes to building climate resilience in communities, involving women is crucial. In fact, the UN reports that communities are more successful in resilience and capacity-building strategies when women are part of the planning process. Moreover, by improving access to clean energy, women death due to toxic fumes and related disease can be reduced by half.

It is therefore essential that climate change mitigation and adaptation strategies adequately take into account women considerations, addressing gender inequality, reduced harms from climate injustice[5] and effective participation at the national and global climate change discussion tables.

Recommendations for engaging women in climate change and energy matters:

 While Tanzania has made some progress in a climate change, significant policy and governance gaps still exist. Addressing these gaps requires strengthening institutional capacity, enhancing coordination, improving legal frameworks, promoting transparency, and ensuring women inclusive decision-making processes backed with sustainable funding. An organ similar to a National Women in Climate Change and Energy Council, could an ideal vehicle for channeling and championing women participation in climate change and energy transition in Tanzania. Conducting periodic women congresses on Climate Change, Gender and Energy Transition would propel this even further.

 Some of our identified and recommended approaches include:

  1. Develop a comprehensive Climate Change Policy for Tanzania to address some of the gaps that exist.  Currently, Tanzania doesn’t have and are fragmented in different  documents such as the National Adaptations Programs, National Climate Response Strategy and the National Strategy for Mainstreaming Gender in Climate Change (NSMGCC). The absence of a comprehensive climate change policy constitutes a huge lacuna that Tanzania must bridge
  2. Creating and convening safe spaces for women dialogue on climate change and energy transition matters is fundamentally urgent. This includes establishing women’s groups, organizing consultations, and ensuring women’s representation in policy dialogues and negotiations at all levels. Women Must talk. It is for this reason that we (GEPC) advocate for a hosting periodic Women National Pan African Congresses on Climate Change and Energy Transition and a Women COP on Climate Change and Energy Transition in the nearest future.
  3. Support and Facilitate Women’s inspired and led participation in Climate Change and Energy transition: This includes encouraging and supporting women’s leadership in climate change and energy sectors by providing mentorship, networking opportunities, and skills development at all levels. In this regard we (GEPC) advocate for establishment of a National Women in Climate Change and Energy Council as a vehicle to advance women concerns and interests in climate change and energy matters. Existing studies support that women’s representation in decision-making bodies, advisory committees, and project management teams is crucial for better resource governance, conservation outcomes, and disaster readiness (Brixi et al., 2022). Moreover, effective participation of women will reduce climate and energy related vulnerability and death by thousands
  4. Promoting Education and Training: Investing in education and training programs to enhance women’s capacity in climate change adaptation, renewable energy technologies, sustainable agriculture, and natural resource management. We advocate for tailored vocational training on climate adaptation and energy transition solutions, workshops on business and enterprise development, and awareness campaigns as essential skills and tools measures to meet women’s specific needs and interests.
  5. Provide access to resources: Government and Private sector must ensure equal and cheap access for women to financial resources, technology, land, and other productive assets necessary for their participation in climate change and energy initiatives. This involves providing dedicated financing lines, affordable microfinance services, facilitating access to clean energy technologies, and promoting resource rights for women. The gaps and vulnerability scores as per current reports (Tanzania Demographic Health Survey and Malaria Indicator Survey TDHS-MIS, 2022) are significantly large and have remained tilted against women.
  6. Promoting and implementation of Gender-Responsive Policies: We advocate for going beyond the integration of gender considerations into climate change and energy policies, programs, and projects. Conducting gender analyses, integration of gender concerns as a distinct feature into project design and implementation are first steps monitoring, evaluating and learning from the gender impacts of interventions and renewed action is essential.
  7. Raising Awareness and Changing Attitudes: Conducting awareness-raising campaigns to emphasize the importance of women’s participation in climate change and energy matters. Challenging stereotypes and social norms that restrict women’s involvement in decision-making processes or limit their access to resources and opportunities is crucial.
  8. Promote Women in Green Entrepreneurship: Encouraging and supporting women entrepreneurs to develop and scale up businesses that promote climate resilience and sustainable energy solutions. Private sector initiatives such as Jasiri Green Bonds is a positive initiative, however the simplicity, affordability and onboarding of more women has to be improved and scaled up purposefully for women. Additionally cheap training, technical assistance, and access to markets must be undertaken to help women establish and grow their enterprises in sectors such as renewable energy, eco-tourism, and sustainable agriculture.
  9. Provide a collaborative and facilitative environment for Civil Society and NGOs to engage: Government, Private Sector and Donors must support, partner and collaborate with Civil Society and NGOs that work on Women and Climate Change and Energy Transition. Over the last years, the civic space and financing for climate rights-based organisations has been constrained.  Research suggests that leveraging on their expertise and networks as allies can enhance women’s engagement in climate change and energy initiatives can deliver more dividends (Nachmany, 2018).

By implementing these strategies and fostering collaboration across sectors, Tanzania can empower women to play a significant role in addressing climate change and driving sustainable energy transitions.

Conclusion:

This policy brief underscores the critical importance of addressing gender disparities in climate change and energy transitions in Tanzania. Both part 1 and 2 of the brief highlights the effects that climate change and energy injustice have on women and the inherent policy, governance and financing gaps that exist in Tanzania’s climate and energy transition space. The brief concludes that  despite the efforts, women are still at the periphery and their active engagement in the current climate change and energy discussions and decision-making processes is imperative to ensure climate change and energy transition interventions are inclusive and effective. By prioritizing gender equality and women’s empowerment, Tanzania can enhance resilience to climate change, address energy injustice, reduce climate change vulnerability and advance sustainable development.

References:

Agora Portal for Parliamentary Development. (n.d.). Climate change, energy, and gender. Retrieved from https://agora-parl.org/resources/aoe/climate-change-energy-and-gender

Brixi, H., Das, J., & Doss, C. (2022). People and planet together: Why women and girls are at the heart of climate action [Blog post]. World Bank Blogs. Retrieved from https://blogs.worldbank.org/en/climatechange/people-and-planet-together-why-women-and-girls-are-heart-climate-action

Energia. (2020). Gender and energy country brief for Tanzania. Retrieved from https://www.energia.org/assets/2021/02/Country-brief-Tanzania_Nov2020_final

Fadhila H.A Khatibu, Razack B. Lokina (2023). A Review of Tanzania’s Fiscal Regime for Climate Action. https://www.repoa.or.tz/wp-content/uploads/2024/03/A-Review-of-Tanzanias-Fiscal-Regime-for-Climate-Action.pdf

Nachmany, M. (2018). Climate change governance in Tanzania: Summary policy brief. Grantham Research Institute on Climate Change and the Environment, London School of Economics and Political Science.

National Climate Change Strategy (2021-2026). Tanzania Government.

National Strategy for Mainstreaming Gender in Climate Change (2023). Tanzania Government.

Tanzania Demographic Health Survey and Malaria Indicator Survey TDHS-MIS. (2022).

UN Women. (n.d.). Fact Sheet: Women, gender equality and climate change. United Nations. Retrieved from https://www.un.org/womenwatch/

UNDP Tanzania. (n.d.). Bridging the gender gap: Empowering women in the agricultural sector. Retrieved from https://www.undp.org/tanzania/news/bridging-gender-gap-empowering-women-agricultural-sector

UNECA. (n.d.). Support for land use planning sees over 2000 women farmers in Tanzania become landowners. Retrieved from https://africa.unwomen.org/en/stories/news/2023/02/support-for-land-use-planning-sees-over-2000-women-farmers-in-tanzania-become-land-owners

[1] https://www.thecitizen.co.tz/tanzania/news/national/roadmap-for-clean-cooking-energy-to-target-rural-masses-3921536

[2] National Climate Change Strategy, 2021-2026

[3] https://www.repoa.or.tz/wp-content/uploads/2024/03/A-Review-of-Tanzanias-Fiscal-Regime-for-Climate-Action.pdf

[4] https://www.thecitizen.co.tz/tanzania/news/national/roadmap-for-clean-cooking-energy-to-target-rural-masses-3921536

[5] https://genderclimatetracker.org/sites/default/files/Resources/Gender-and-the-climate-change-agenda-212.pdf